Understanding the Federal Reserve, article 6/20
On Wall Street, the same payroll report can support both bulls and bears: jobs beat forecasts while household-survey unemployment unexpectedly rises; softer monthly hourly earnings suggest cooling wage inflation while earlier payrolls are revised sharply lower. Markets pursue a black-and-white trading signal, but the Fed has no mechanical rule saying a particular payroll gain inevitably means a hike or a particular unemployment rate immediately means a cut. Historical data undergo frequent, substantial revision, and different statistical definitions often point in opposite directions at the same time.
The deeper constraint is the statutory dual mandate itself. Price stability has a clear 2% long-term anchor, but maximum employment is unobservable and shifts with demographics and productivity. Monetary transmission also takes several quarters or even two years: today's rate prescribes treatment for tomorrow's economy. Reading data is not arithmetic applied to historical reports. It is continuous balancing of underlying trends, shock characteristics and future risks amid noisy, contradictory information.
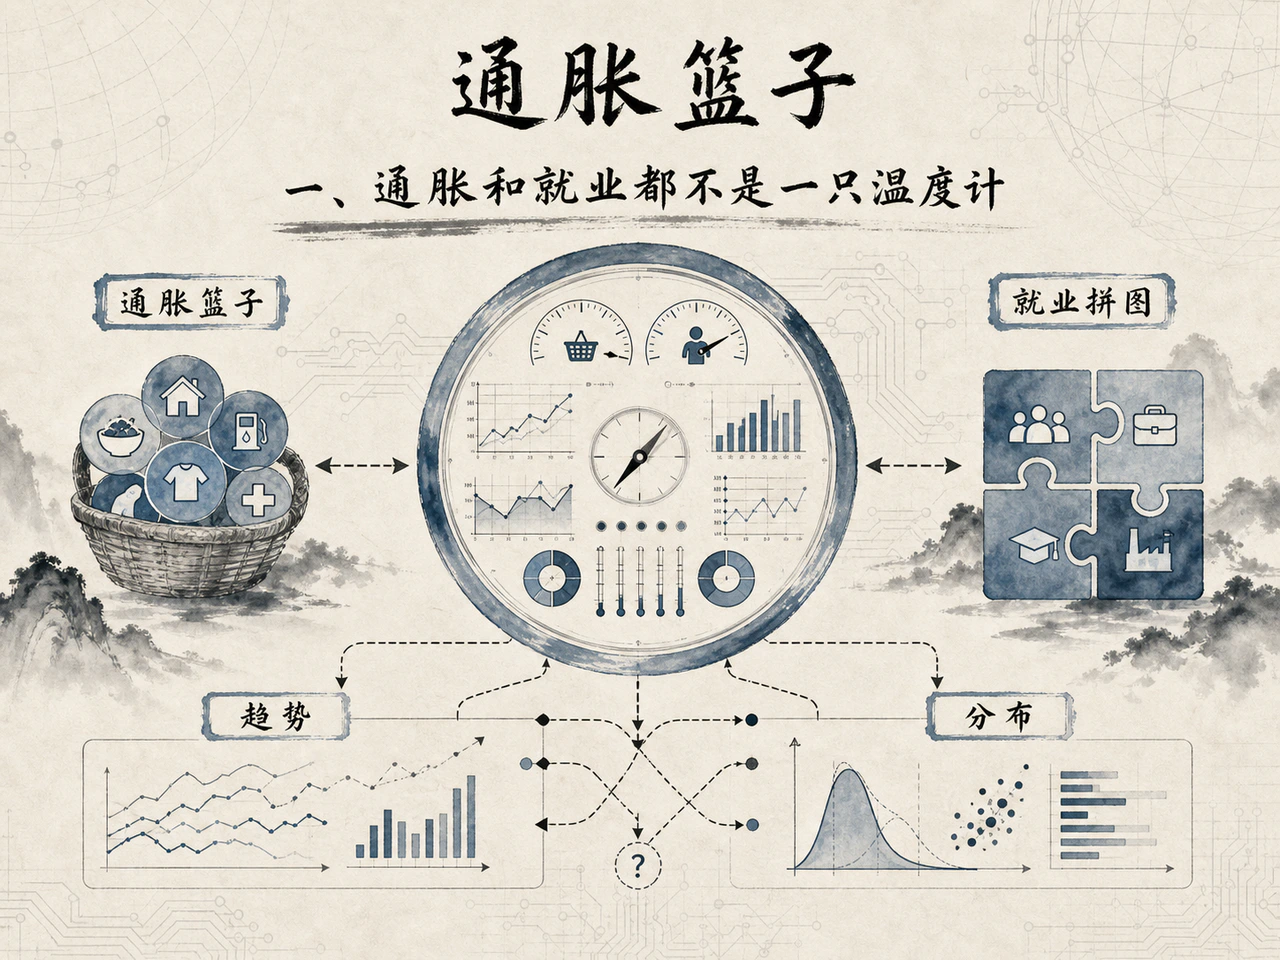
1. Inflation and employment both require a dashboard
Do CPI and PCE measure the same thing?
Both measure consumer-price changes, but differ fundamentally in methodology, coverage and weight updates. BLS publishes CPI, surveying a basket purchased out of pocket by urban households. BEA's PCE price index is directly linked to personal consumption in GDP and has much wider coverage.
Health care is the central difference. CPI includes only households' out-of-pocket expenses, while PCE fully includes large payments made by employer health insurance, Medicare and Medicaid. CPI uses relatively fixed basket weights and responds more slowly even with chain adjustments. PCE uses a Fisher chain index that dynamically captures substitution: when beef becomes expensive and consumers buy chicken, it promptly reflects the basket change, reducing upward overstatement of living costs.
The FOMC establishes 2% annual headline PCE inflation as its statutory long-term inflation objective. It nevertheless cannot ignore CPI, which arrives about two weeks earlier each month and directly anchors most financial derivatives, TIPS, commercial leases and Social Security benefits. CPI provides the initial inflation impulse; PCE calibrates the fuller picture.
Central banks also apply several filters:
- Headline and core inflation: Headline measures the purchasing-power loss households actually face. Core removes volatile food and energy to filter short-term supply disruption and identify underlying trends. Removal is imperfect: if an energy crisis becomes broad transport-cost inflation, logistics premiums and ultimately embedded services wages, focusing only on core may overlook second-round effects spreading into expectations.
- Trimmed-mean and median inflation: Dallas Fed Trimmed Mean PCE and Cleveland Fed Median CPI remove extreme monthly price increases and declines and focus on the middle of the distribution, more cleanly excluding isolated events' influence on the aggregate.
- Supercore: Core services excluding housing. Because rents and owners' equivalent rents are measured with lags, labor-intensive nonhousing services are often treated as the clearest thermometer of domestic labor tightness and endogenous wage pressure.
The observation window also shapes judgment. Year-on-year readings are smooth but vulnerable to base effects from 12 months earlier. One-month annualized changes respond fastest but contain seasonal-adjustment noise. A mature framework overlays one-month momentum, three- and six-month annualized trends and the 12-month cumulative level, avoiding conclusions from one window.
Employment measures conflict for specific reasons
The monthly jobs report combines two independent, nonoverlapping surveys:
- Establishment survey: Payroll records from tens of thousands of nonfarm firms and government agencies produce job gains and average hourly earnings. It captures changes in jobs, but is affected by birth-death-model extrapolation and cannot identify one person holding multiple jobs.
- Household survey: Interviews with tens of thousands of households produce unemployment, participation and self-employment measures. It counts people's employment status and is more sensitive to population movement, but has high monthly sampling variance and volatility.
Rising unemployment alongside booming payrolls can simply mean immigration or returning jobseekers expand the labor-force denominator faster than hiring absorbs them, an improvement in supply rather than collapsing demand. Conversely, falling unemployment with plunging participation signals discouraged workers leaving active search and thus the denominator.
Beyond those aggregates, the Fed cross-checks labor-market flows:
- JOLTS vacancies and quits: The vacancy-to-unemployment ratio gauges job saturation. The quits rate measures workers' confidence: people voluntarily leave when confident in outside opportunities, often leading overall wage growth by several months.
- Initial and continuing unemployment claims: Weekly high-frequency leading indicators quickly reveal marginal layoff developments.
- Employment Cost Index: Unlike average hourly earnings, which change with high- and low-paid employment composition, ECI fixes the occupational mix and is the Fed's benchmark for underlying compensation pressure.
Law sets no rigid unemployment number for maximum employment. Aging, immigration, digitization and skill matching constantly reshape labor capacity. Slightly higher unemployment with steadily falling vacancies and wages converging toward long-term productivity often means healthy rebalancing along the Beveridge curve. Rising unemployment alongside surging claims, full-time-to-part-time shifts and loan defaults instead signals an approaching nonlinear adverse layoff cycle.
2. Rate judgments must connect growth, finance and local conditions
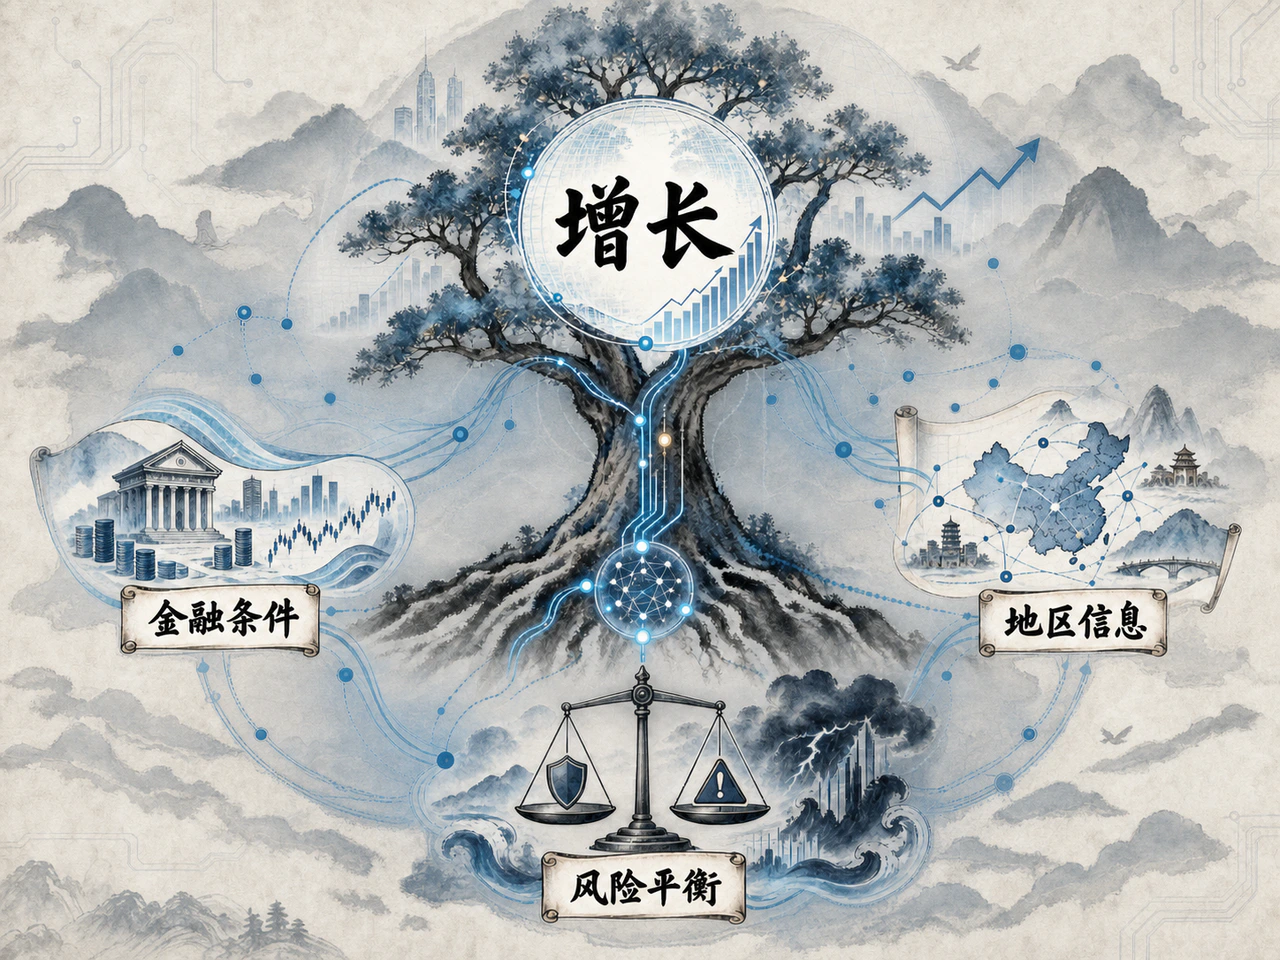
Fast growth does not necessarily mean overheating
High GDP alone cannot justify tightening. The key is whether demand or supply drives growth.
If real growth comes from overstretched consumer credit and fiscal stimulus, the output gap widens, demand presses against supply and inflation returns. If legal immigration expands labor or technology and equipment lift total-factor productivity, potential GDP itself rises. Such supply-led expansion permits healthy real growth with low or falling inflation and need not be crushed by the central bank. Distinguishing the two requires looking through inventories and net exports to final sales to private domestic purchasers, stripped of external disturbances, and comparing nominal income with real output growth.
The policy rate also differs from the restraint the economy actually experiences. The Fed directly controls only overnight interbank borrowing costs. Corporate investment, homebuying and consumption depend on broader financial conditions.
Even with an unchanged FOMC decision, market expectations can transform conditions:
- If markets anticipate cuts, lower ten-year Treasury yields, narrower credit spreads, higher equities and a weaker dollar can spontaneously ease finance and offset the restriction from high policy rates;
- Conversely, if banks raise lending thresholds under credit pressure, as shown in SLOOS, real-economy credit contraction makes the same benchmark rate feel more restrictive.
The central bank must assess the final liquidity environment after policy passes through bond spreads, equities, FX and bank lending gates.
Financial stability is the mandate's hidden foundation. A valuation correction alone does not justify cuts. But sudden bond-market illiquidity, runs on key financing intermediaries or systemic bank withdrawals can interrupt transmission. The usual response is targeted tools—discount window, emergency lending facilities and currency swaps—to repair market functioning while separating lender-of-last-resort duties from the overall monetary stance. This avoids hastily changing macro rates to address a localized structural liquidity shock.
The Beige Book captures changes not yet in statistical tables
Beyond backward-looking hard data, the Fed maintains a soft-information radar reaching into the real economy.
Published eight times a year by the 12 regional Feds, the Beige Book is crucial qualitative intelligence before FOMC meetings. Research teams visit retailers, plant managers, freight hubs, union representatives and community bankers to record firsthand conditions. Trends appearing in official data only months later—broad consumer down-trading, hidden hiring freezes, small firms defaulting on commercial lease renewals or suppliers quietly discounting inventory—often emerge first in these grassroots interviews.
Regional manufacturing and services diffusion surveys, such as Empire State and Philadelphia's Business Outlook, quantify new orders, unfilled orders, prices paid and hiring intentions monthly in positive or negative diffusion territory.
These reports cannot replace rigorous national accounts. They function as geographically distributed early-warning radars, detecting hints of changing direction and prompting policymakers to check whether models are departing from reality before national hard data arrive.
3. The dot plot is conditional judgment, not a rate contract
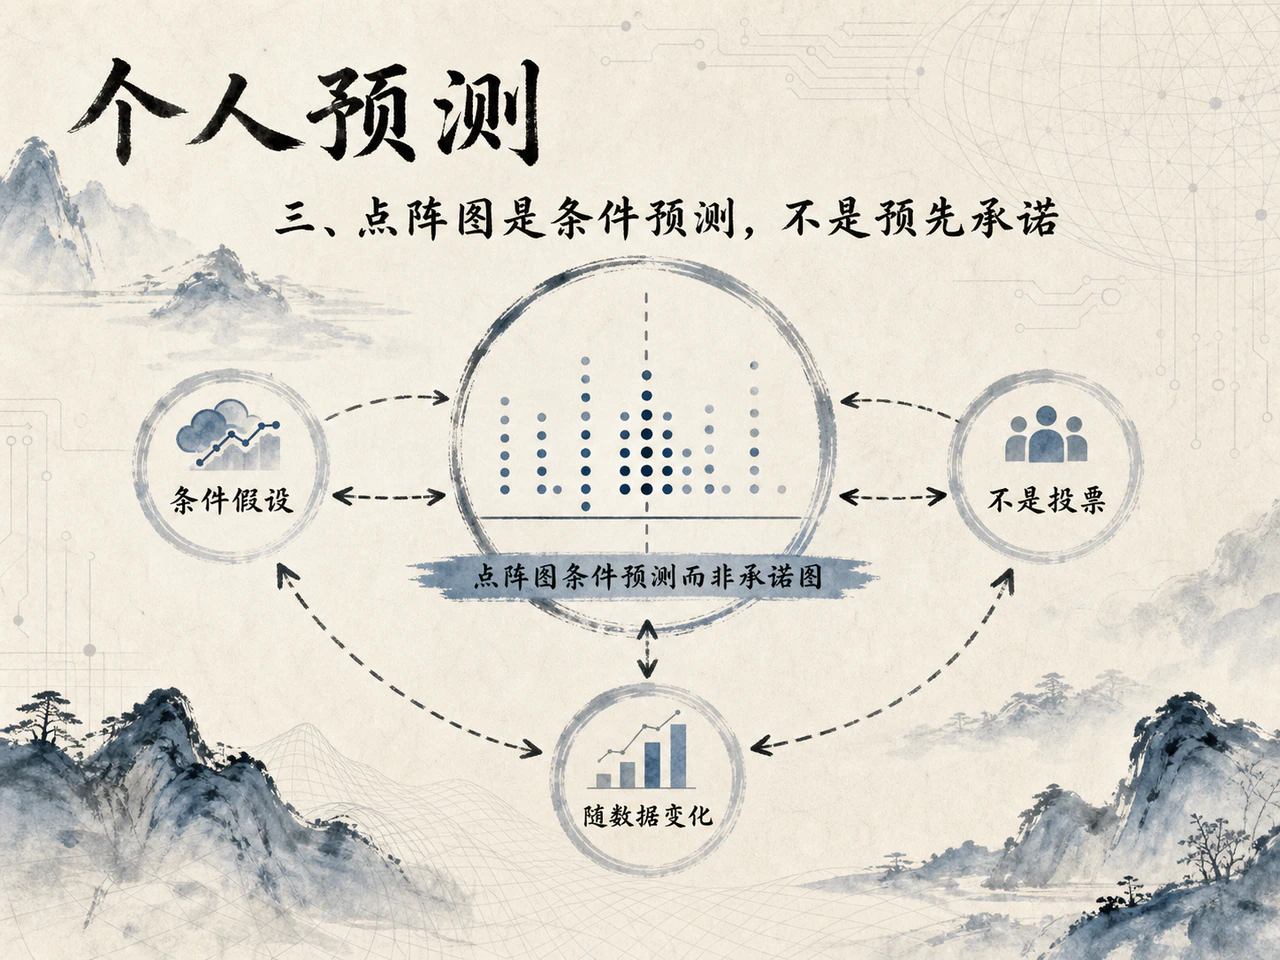
Every SEP dot carries its own assumptions
The Summary of Economic Projections released at March, June, September and December FOMC meetings often triggers volatility. Its dot plot records independent forecasts by all 19 participants, voting or not that year, for future years and the longer-run neutral rate.
Four misconceptions need clearing up:
- Different endogenous assumptions: Dots are not objective forecasts under one shared path. A hawk may assume two more hikes are needed to suppress inflation; a dove may believe current restraint is sufficient for natural disinflation. Each incorporates that official's view of appropriate policy rather than a unified committee exercise.
- Dots carry no weights: All 19 anonymous dots look equal. In practice, the chair, vice chair and New York Fed president have much greater influence than more peripheral or nonvoting regional presidents. Equating the arithmetic mean or median of 19 dots with the chair's eventual will can badly mislead.
- The median is not a collective vote: The plot displays a dispersed collective tendency, not committee legislation or a joint decision. It has no legal force or majority-rule obligation.
- Strong conditionality: Every dot is constrained by information known on the meeting date. Unexpected changes in geopolitics, commodity supply or credit transmission can immediately invalidate the assumed path. Treating it as a fixed-rate contract leads markets to accuse the Fed of reneging or losing credibility when changed conditions require a different pace.
Ask four questions before judging rates
An effective way through market noise is not betting on one surprise, but continually tracing four chains in the Fed's reaction function:
- Is inflation a question of speed, or of persistence and breadth?
Examine whether improvement comes only from external relief such as lower oil and repaired supply chains, or has reached rents and core services. Are long-term expectations, in surveys or traded inflation compensation, still firmly anchored near 2%? - Is the labor market cooling healthily or entering a nonlinear stall?
Are fewer vacancies and easier hiring rebalancing supply and demand, or are squeezed corporate cash flows triggering layoffs and deleveraging? Historically, labor markets absorb initial tightening smoothly, but once unemployment crosses a critical threshold, triggering the Sahm rule, a self-reinforcing downward spiral can form quickly. - Is the shock to supply, demand or financial liquidity?
Overheating demand calls for high rates. Tightening cannot produce crude or repair ports when supply bottlenecks such as Red Sea disruption or crop failures raise prices, and indiscriminate tightening can deepen output losses. Local financial-liquidity breaks require specific channels, without confusing tool functions. - How restrictive are conditions in reality, and is restraint accumulating or intensifying?
With nominal rates unchanged, falling expected inflation automatically raises the real rate—nominal rates minus expected inflation—creating passive tightening. Is the real rate far above the natural neutral rate, r*? Is policy orderly in suppressing overheating, or quietly accumulating irreversible lagged damage within the economy?
Data dependence is not dependence on every data point. It means continuously updating understanding of macroeconomic mechanisms and asymmetric risks as information emerges. The alternative is a mechanical response without macroeconomic perspective, driven by short-term market noise.
Data never press the committee's voting button. Without certain answers, the relevant question is not how far one month's jobs or inflation missed expectations, but which belief about economic resilience the release changed, and which error policymakers can least afford today: renewed inflation or a premature labor-market stall.