By the afternoon of October 25 Beijing time, S&P Dow Jones Indices’ changes to its U.S. growth and value index methodologies continued to attract attention in Chinese and international financial markets. Under the decision announced on October 23, the changes would take effect before the U.S. market opened on December 21. Value assessment would incorporate intangible-asset adjustments, forward earnings and free cash flow, while growth assessment would drop the preceding 12 months’ share-price appreciation. Bloomberg Intelligence analyst James Seyffart estimated that passive funds tracking the affected indices held at least US$375 billion in assets.
The reform raised a valuation question more fundamental than the year-end rebalance. As modern companies increasingly generate earnings through research, software and organizational capabilities, how well does conventional book equity represent the economic capital investors are buying? Under the old rules, sustained high R&D spending could make companies appear expensive on price-to-book measures because the expense directly reduced current profit and equity. Cyclical companies whose shares had surged over the preceding year could meanwhile receive substantial allocations to growth indices because of strong price momentum. Fund names stayed the same, but their underlying selection logic could diverge from investors’ intuitive understanding.
The core aim was to make style classification better reflect actual business operations and valuations. The rules would directly change some stocks’ allocations between growth and value portfolios and trigger year-end rebalancing by linked funds. Whether better rules produced better returns still depended on companies converting intangible investment into free cash flow, the valuations investors paid, and the secondary market’s ability to absorb the rebalance trades.
1. Growth drops 12-month price momentum; value adds intangible assets, forward earnings and free cash flow

S&P’s existing growth score used three core measures together: the three-year net change in earnings per share relative to the current share price, the three-year growth rate in sales per share, and share-price appreciation over the preceding 12 months. The first two described fundamental business expansion; the third measured the price trend already delivered by the secondary market.
Including price momentum directly in the definition of growth could produce sharp shifts in sector and style exposures with short-term markets. Reviewing S&P’s December 2022 annual reconstitution, WisdomTree chief investment officer Jeremy Schwartz noted that energy’s weight in the S&P 500 Value Index fell by about 6.5 percentage points, while the Growth Index substantially increased exposure to traditional sectors including energy. Energy shares had led the U.S. market in 2022, lifting their growth scores through momentum, while some technology companies whose shares had fallen sharply migrated toward value. This showed clearly that growth and value under index rules were never fixed synonyms for technology and traditional industries.
Once 12-month price appreciation was removed, a stock would no longer receive a direct growth-factor boost simply because its price had surged over the preceding year. A company with strong fundamental growth but temporarily weak shares would also cease to be penalized by negative price momentum. However, the retained earnings-change measure still used the current share price as its denominator, and price changes would still affect composition through market-cap weighting. The relationship between the growth index and market price trends would therefore remain.
While growth assessment removed a factor, value assessment expanded substantially:
| Measure | Previous rule | New rule |
|---|---|---|
| Book value | Book equity per share relative to price | Intangible-adjusted book value per share relative to price |
| Earnings | Historical earnings per share relative to price | Simple average of historical and one-year forward earnings yields |
| Sales | Sales per share relative to price | Retained |
| Cash flow | No separate value factor | Adds free cash flow per share relative to price |
Forward earnings were intended to incorporate operating expectations not yet captured in historical accounts. With the share price unchanged, if expected earnings over the next year were below historical earnings, the simple-average blended earnings yield would be lower than the purely historical measure. Improving expected profits would raise it. Combining realized results with one-year expectations meant that forecast revisions would affect the value score.
All four value measures used the current share price as their comparison base. Book assets, earnings and cash generation could support a judgment about cheapness only relative to the market value investors paid. Cash-flow structures differ fundamentally across industries, however, and imposing an industrial-company free-cash-flow standard could introduce measurement bias. S&P specified that certain financial and property categories, including real estate, banks and insurers, would not use the free-cash-flow factor; their value scores would combine the other three measures.
The changes covered S&P’s standard Style and Pure Style index families across market-cap series including the S&P 500, MidCap 400 and SmallCap 600. Admission criteria for parent indices such as the S&P 500 itself were unchanged. S&P Dow Jones Indices would begin providing pro forma files to clients on December 4, showing detailed constituent weight reallocations under the new methodology.
2. Intangible adjustments can correct R&D-heavy companies’ price-to-book ratios, but past spending is not future cash flow
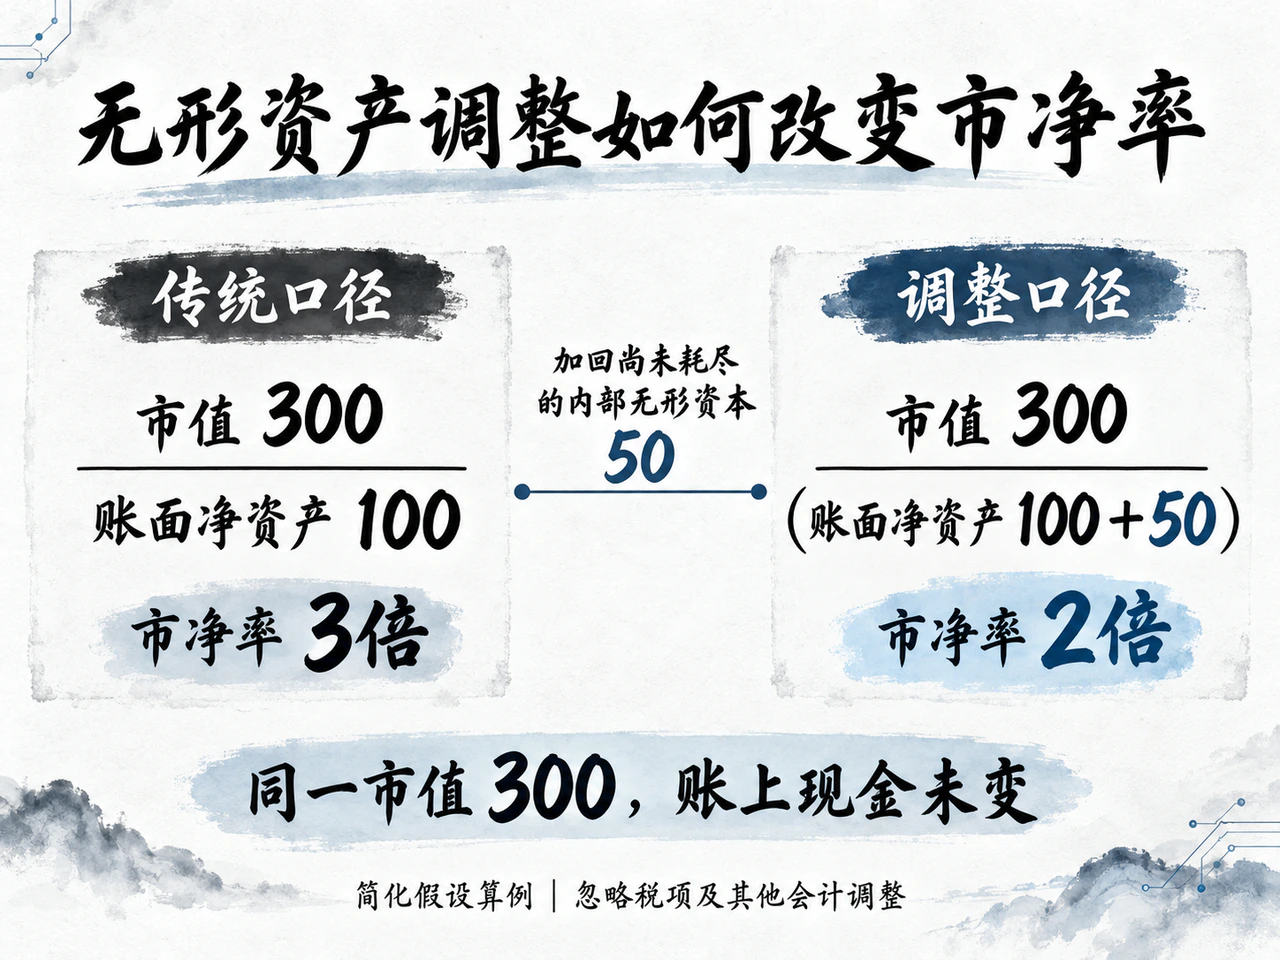
One important source of distortion in conventional price-to-book ratios is the different accounting treatment of tangible and intangible investment. A machine usable for several years is first recognized as a fixed asset and depreciated over its useful life, leaving the unconsumed capital cost on the balance sheet. Under U.S. generally accepted accounting principles (US GAAP), internally undertaken R&D is usually fully expensed when incurred. Even if it generates revenue for years, that potential economic capital does not appear in book equity.
Over time, this difference can substantially depress R&D-intensive companies’ book equity and raise their apparent price-to-book ratios. In a simplified example ignoring taxes and other accounting adjustments, suppose a company has a market capitalization of 300 and reported equity of 100, giving a price-to-book ratio of three. If historical R&D and other spending imply another 50 of unconsumed internal intangible capital, adding it back to analytical equity reduces adjusted price-to-book to two. Neither market capitalization nor cash changes; reconstructing the valuation denominator changes the ratio.
Turning that arithmetic into cross-industry index rules requires difficult parameter choices. Which R&D expenditures become durable assets? What share of selling, general and administrative expenses (SG&A) builds brands, customer relationships and organizational capabilities, and what share merely sustains current operations? How long do those assets last? Adding back all historical spending would struggle to distinguish productive investment from wasted costs and could double-count identifiable intangibles recognized in acquisitions or software costs already capitalized on the balance sheet. International Financial Reporting Standards (IFRS) also already allow qualifying development-phase costs to be capitalized, so the U.S. logic cannot be mechanically transferred to other markets.
Academic estimates of intangible capital depend heavily on depreciation rates and capitalization assumptions. In a paper revised in 2023, Michael Ewens and coauthors used actual prices in acquisitions, bankruptcies and liquidations to calibrate parameters. They estimated an average annual R&D capital depreciation rate near 33%, well above the 23% comparison benchmark common in the literature. The share of SG&A identifiable as long-term investment ranged from 20% to 51% across industries. The same historical financial statements can therefore produce materially different adjusted equity under different useful-life and capitalization assumptions. These were academic estimates, not the specific parameters adopted for S&P’s index methodology.
In general financial analysis, capitalizing intangible investment changes the cyclical behavior of earnings as well as the balance sheet. The earnings-factor change explicitly announced by S&P was the average of historical and forward earnings yields. In a generic capitalization framework, qualifying current R&D is added back to profit and amortization of earlier capitalized investment is deducted. During rapid R&D expansion, new investment exceeds amortization of the accumulated stock, depressing reported profit under immediate expensing. In a steady state, current additions and amortization converge. If R&D is cut sharply, previously accumulated intangible capital still needs amortizing, and adjusted earnings may fall below reported earnings.
The principal role of intangible adjustment is thus to improve valuation comparability across business models. It neither changes the cash already consumed by R&D nor guarantees a future return on historical spending. Failed technology paths, obsolete product generations or lost core customers can accelerate the depreciation of estimated intangible capital. Whether a company truly has a valuation margin of safety ultimately depends on converting that spending into future cash earnings.
This also explains why adjusted book assets and free cash flow are useful together. An asset-light company may no longer look expensive on intangible-adjusted price-to-book because of years of R&D and brand investment. Yet if it must maintain heavy R&D and capital spending to defend market share, its free-cash-flow yield may remain unattractive. The four value factors can reinforce or offset one another. High R&D spending alone does not imply that a stock’s value-index weight must increase.
3. Intangible value improved long–short backtest returns by 2.4 percentage points a year, without removing value’s weakness in some periods
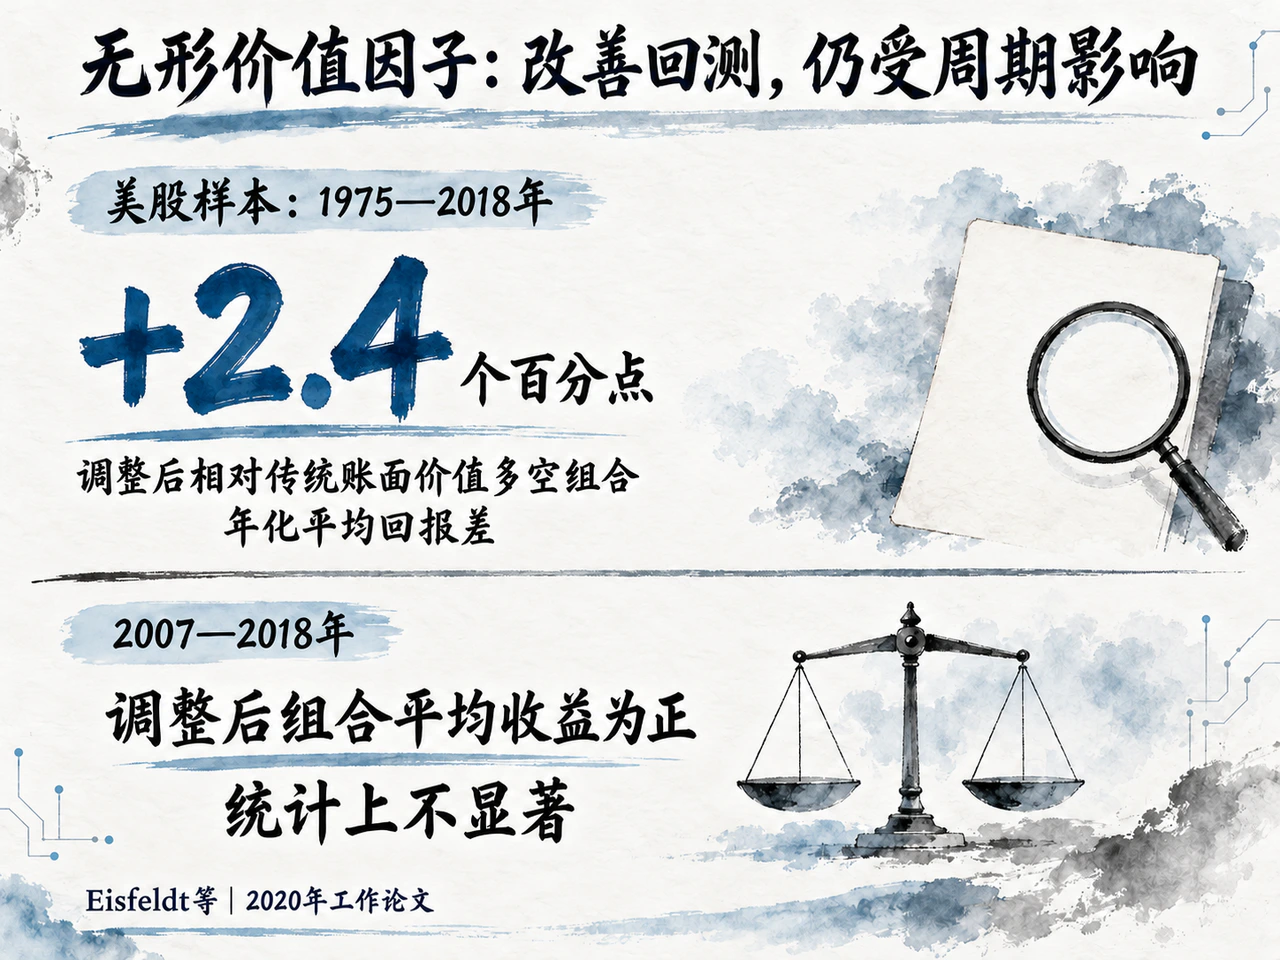
Empirical research on intangibles provides a more rigorous quantitative basis than the claim that price-to-book simply does not apply to technology. In Intangible Value, Andrea Eisfeldt, Edward Kim and Dimitris Papanikolaou incorporated internally generated intangible capital into book-value rankings for U.S. stocks over 1975–2018. Under the measures reported in their 2020 working paper, a portfolio long stocks with high adjusted book-to-market ratios and short those with low ratios delivered an annualized mean return approximately 2.4 percentage points above a conventional book-value long–short portfolio.
A long–short portfolio measures the relative return between cheaper and more expensive groups, rather than the actual return of a long-only index fund. The same paper showed that over 2007–2018, a difficult period for value strategies overall, the intangible-adjusted value portfolio’s average return was positive but not statistically significant. Correcting an omission in conventional book assets improved relative performance in that sample, but did not guarantee a persistently significant excess premium in every market cycle.
Another study covering multiple valuation measures reached a more cautious conclusion. Ronen Israel and coauthors’ 2021 paper systematically compared conventional book value, historical earnings, forward earnings, sales and cash flow, and specifically tested the HOLT cash-flow valuation approach with its extensive accounting adjustments. Comparisons of two-year rolling risk-adjusted returns from February 2014 through May 2020 showed that value’s cyclical weakness did not disappear with these adjustments or additional factors.
Both strands of evidence point to a clear pricing logic. Conventional price-to-book does omit intangible economic capital, but that measurement bias was not the whole explanation for value’s weakness over the periods studied. Valuation multiples can remain detached from fundamentals for long periods; apparently cheap companies can become value traps as operations deteriorate, while expensive growth businesses can repeatedly beat earnings expectations. Better index selection measures can make classification more economically realistic, but cannot remove business execution risk or market valuation cycles.
Likewise, historical backtest improvements cannot simply be extrapolated into a new index’s future returns. S&P was changing several factors on both the growth and value sides at once. The result would depend on relative constituent rankings and weight calculations across the market. For example, an R&D-intensive company with weak share-price performance but strong revenue and earnings growth might gain in growth score when momentum was removed and also gain in value score after intangible adjustment. Its final weight changes in the two indices would depend on the relative changes in both scores and on other constituents’ score distributions.
Index providers were taking different approaches to the same problem. In an October consultation, FTSE Russell favored adding sales-to-price alongside book value and examined ways to reduce distortions caused by concentrated mega-cap technology exposure. Its approach emphasized underlying data coverage, time-series stability and turnover costs, rather than copying S&P’s four-factor system. FTSE Russell’s proposal was still open for public comment, with a December 11 deadline, and had not been finalized. It should not be confused with S&P’s confirmed December 21 implementation.
Methodology differences mean that funds carrying the same value or growth label can have materially different holdings and risk exposures when they track different index families. Evaluating them requires examining whether their factors capture sustainable earnings and cash flow, suit the business characteristics of the industries held, and impose hidden turnover costs. Counting factors or comparing backtest curves alone is insufficient.
4. US$375 billion is linked assets, not trading volume; fund size and weight changes jointly determine net stock demand
Two stages separate a methodology change from actual secondary-market trades: index classification and weighting, then fund execution. In S&P’s standard Growth and Value indices, a stock can be allocated proportionally to both portfolios. Becoming more value-like often means a larger value allocation and smaller growth allocation, rather than an all-or-nothing switch. Each index then calculates portfolio weights and applies concentration constraints. Pure Style indices instead prohibit constituent overlap and weight directly by style score rather than market capitalization. Their rule changes can therefore alter both membership and weights.
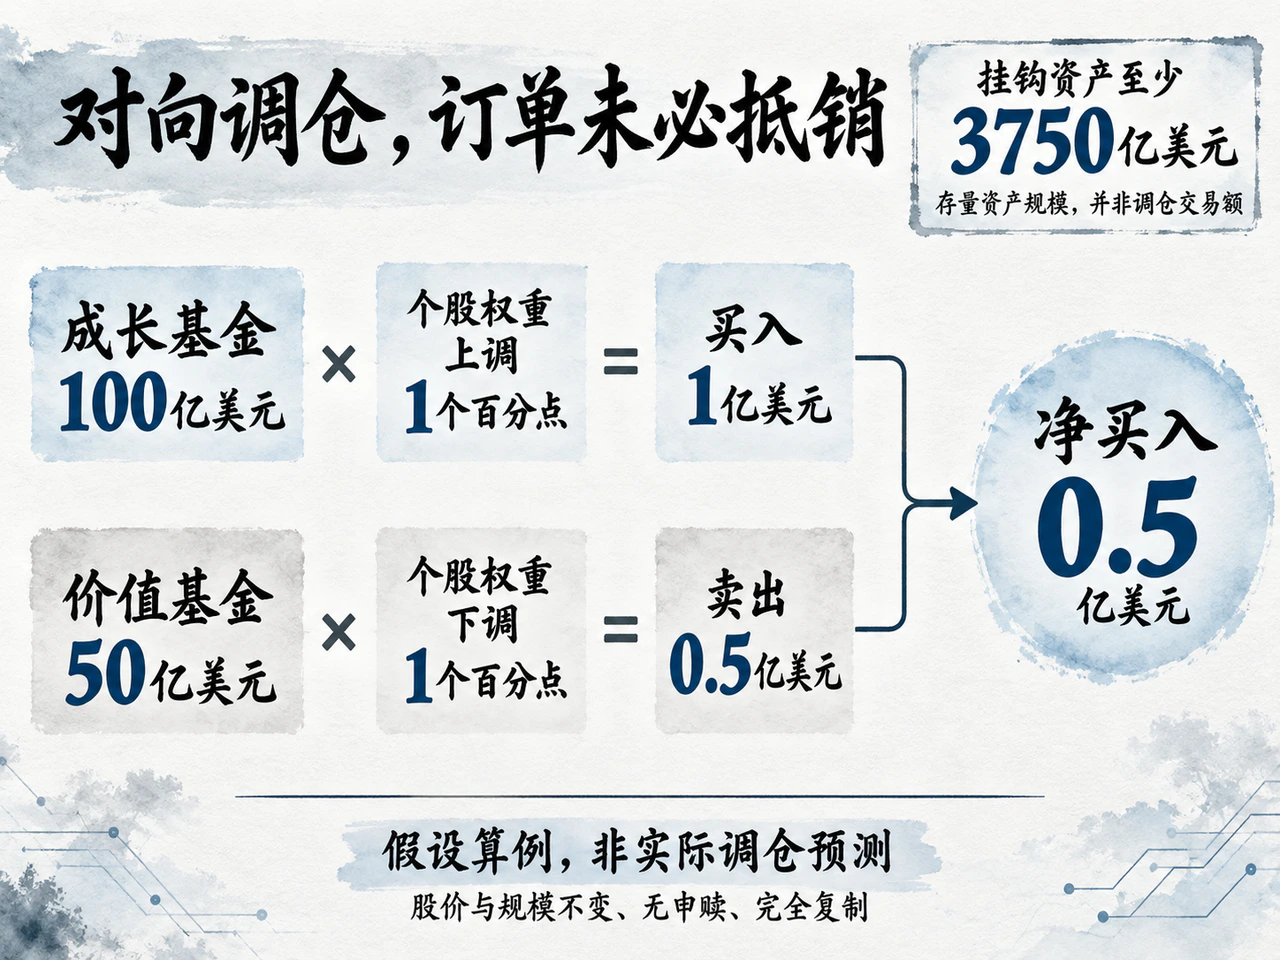
Bloomberg Intelligence’s estimate of at least US$375 billion referred to the existing assets of passive funds tracking the relevant indices, rather than an amount that would all turn over in December. Funds needed only to trade the differences between old and new target weights, selling some stocks whose weights fell and buying others whose weights rose. The rebalance itself did not represent fresh outside capital entering U.S. equities.
Even when the growth and value weight changes for one stock point in opposite directions, the resulting orders need not cancel in the market. One reason is that assets linked to the two sides are unequal. Official iShares data at October 23 put net assets of the S&P 500 Growth ETF, IVW, at approximately US$75.441 billion and those of the S&P 500 Value ETF, IVE, at about US$50.403 billion. That flagship pair alone had an asset gap near US$25 billion. The broader affected universe also included other managers, MidCap 400 and SmallCap 600 products, and Pure Style ETFs.
A simplified example shows how size differences drive net flows. Suppose a growth fund has US$10 billion and the corresponding value fund US$5 billion. Assume unchanged prices and fund sizes, no subscriptions or redemptions, and full replication. If a stock’s target weight rises one percentage point in growth and falls exactly one percentage point in value, the growth fund must buy US$100 million and the value fund sell US$50 million, leaving net market buying of US$50 million. Actual index calculations need not produce symmetric weight changes on the two sides.
Estimating a real stock’s rebalance impact also requires accounting for deviations in existing fund holdings, share-price moves during the trading window, ordinary subscriptions and redemptions, cash management, and execution choices such as sampling, staged trades or in-kind transactions. The price effect depends on net orders aggregated across the market relative to normal trading liquidity and the prices at which active investors and other counterparties are willing to provide it.
Historical evidence also shows that growth in passive assets does not translate proportionally into a larger index effect. In a 2022 working paper on S&P 500 membership changes, Robin Greenwood and Marco Sammon found that newly included stocks’ average market-adjusted excess return from the session before announcement to the session after implementation had fallen from approximately 7.6% in the 1990s to about 0.8% in 2010–2020, with the latter no longer statistically significant. One important mechanism was offsetting sales by funds tracking a stock’s previous index when it migrated. Parent-index membership events cannot be directly applied to this style reconstitution, but the evidence likewise shows why the headline US$375 billion cannot establish year-end price pressure without considering offsetting orders and liquidity.
Current holdings also caution against interpreting the reform as technology entering value for the first time. As of October 22, information technology already represented approximately 20.21% of the S&P 500 Value ETF, IVE. What mattered after implementation was the marginal change in constituent lists, sector allocations and valuation characteristics, together with the associated portfolio turnover costs.
The most direct effect was the redistribution of existing U.S. equity holdings among passive investors with different style preferences, reshaping the sector and factor exposures of related ETFs. Cash used for secondary-market rebalance purchases went directly to the selling counterparties. Only if sustained style demand subsequently changed companies’ secondary-market valuation levels and refinancing costs would index methodology affect operating businesses indirectly through later equity issuance, acquisitions, restructuring and capital spending decisions.
For portfolio investors, adding intangible capital, forward earnings and free cash flow rebuilt the underlying definitions of value and growth used by passive products. Ahead of year-end rebalancing, investors first needed to check the full benchmark name in their fund prospectus, distinguishing standard from Pure Style and large-cap from mid- or small-cap indices. Available client pro forma files and public holdings after December 21 could then reveal the actual sector weights and valuation exposures. Measures better suited to modern business models can reduce accounting distortions, but long-term returns still depend on companies converting R&D and intangible investment into cash-generating free cash flow, and on purchase prices leaving an adequate margin of safety.


