U.S. July PPI and weekly claims released August 13 strengthened the case for a September hold. Headline inflation cooled without a labor-market collapse, shifting debate from immediate defensive hikes toward waiting for more evidence.
Headline prices cool while core components stay sticky
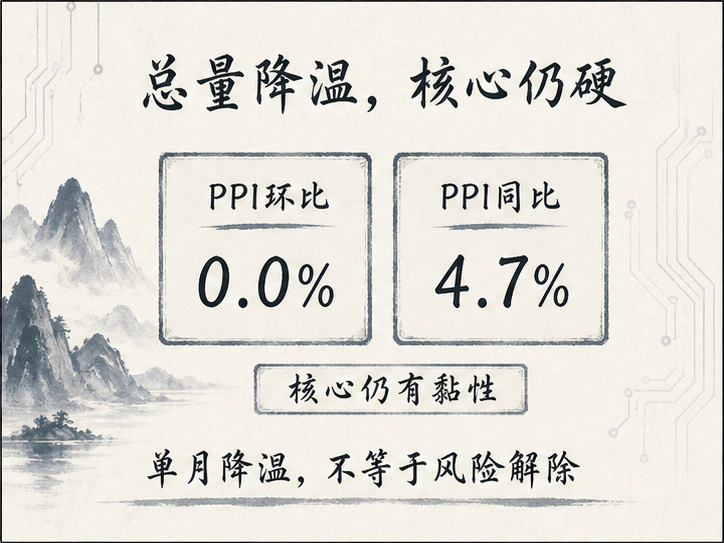
July final-demand PPI was unchanged, 0.0%, below the 0.2% consensus and following June's 0.1% decline. Annual growth slowed from 5.5% to 4.7%.
In July, commodity and energy weakness drove the moderation. Final-demand goods fell 0.7% monthly, energy 3.1% and wholesale gasoline 5.7%. Services remained resistant, rising 0.2%.
More importantly, PPI excluding food, energy and trade services still rose 0.4%. Energy made the headline mild, but deeper and intermediate price pressures had not cleared, insufficient for the Fed to conclude inflation risks were gone.
September hike expectations recede: a pause rather than a dovish turn
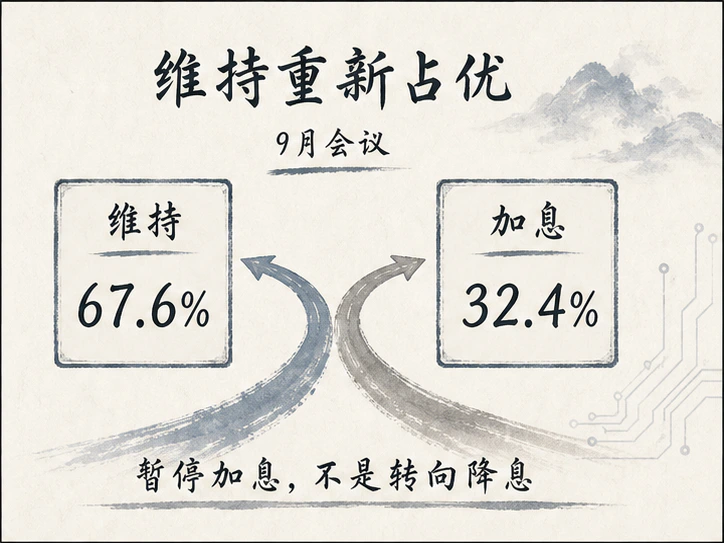
Derivatives repriced quickly. August 13 CME FedWatch put holding the 3.50%–3.75% range in September at about 67.6% and a 25-basis-point hike at 32.4%, versus hike odds of 40.6% the previous trading day and 55.0% a week earlier.
This was a pause trade, not a bet on cuts. With sticky core services and annual inflation well above the 2% statutory target, the Fed could not at that point signal a premature dovish pivot.
With no official speeches, minutes or policy documents in the current window, high-frequency fundamentals almost entirely drove the expectation swings.
Very low layoffs give the Fed room to wait
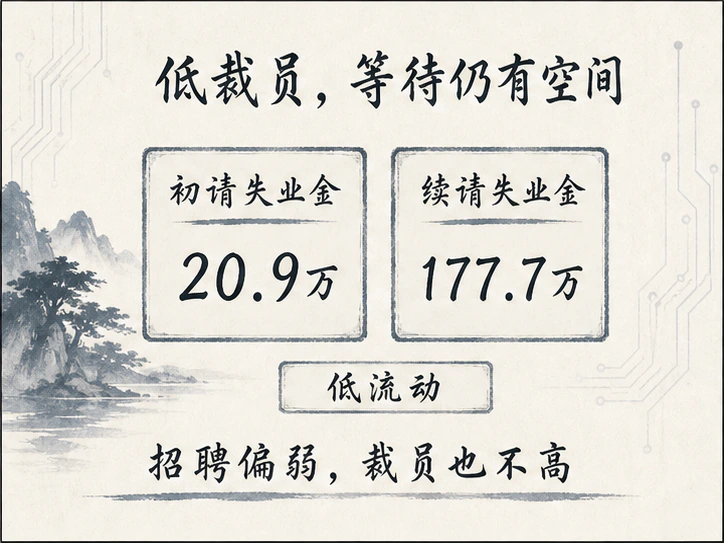
Labor data also supported patience. Initial claims in the week ending August 8 rose 9,000 to 209,000, slightly above Bloomberg's 204,000 consensus but still historically very low. Continuing claims for the week ending August 1 fell 22,000 to 1.777 million.
Hiring and job creation were slowing, but layoffs remained minimal, leaving a low-hiring, low-firing equilibrium. Without broad unemployment signaling recession, the Fed had no need to act hastily to support growth.
Attention would turn to July core PCE, August payrolls and August CPI. Renewed external energy pressure alongside resilient employment would keep hikes available. Disinflation spreading to services with gradual labor softening would sustain a hold-and-observe stance as the clearest baseline for coming months.


