On August 14, US stocks consolidated slightly below record highs. The S&P 500, Nasdaq 100 and Dow fell 0.17%, 0.13% and 0.20%, respectively, while VIX eased from 14.63 to 14.25. Index performance alone suggests an uneventful pre-weekend close. Put consumption, Treasury structure, commodities and FX together, however, and the underlying signals are less reassuring.
July US retail sales fell 0.6% month on month, confirming emerging fatigue in final demand. Traditionally, weak data should lower risk-free rates and support equity valuations. Yet the entire closing Treasury curve moved higher: the 10-year reached 4.68% and the 30-year 5.25%. WTI and gold rose together.
Markets did not simply turn weaker consumption into an easing dividend. Growth concerns rose, but reflation persistence, wider term premiums and high long-term capital costs remained firm constraints. Calm indexes concealed changing valuation logic, making a tougher earnings and cash-flow test unavoidable at elevated equity levels.
Consumption Slows Markedly, but Divergence Does Not Yet Signal Systemic Collapse
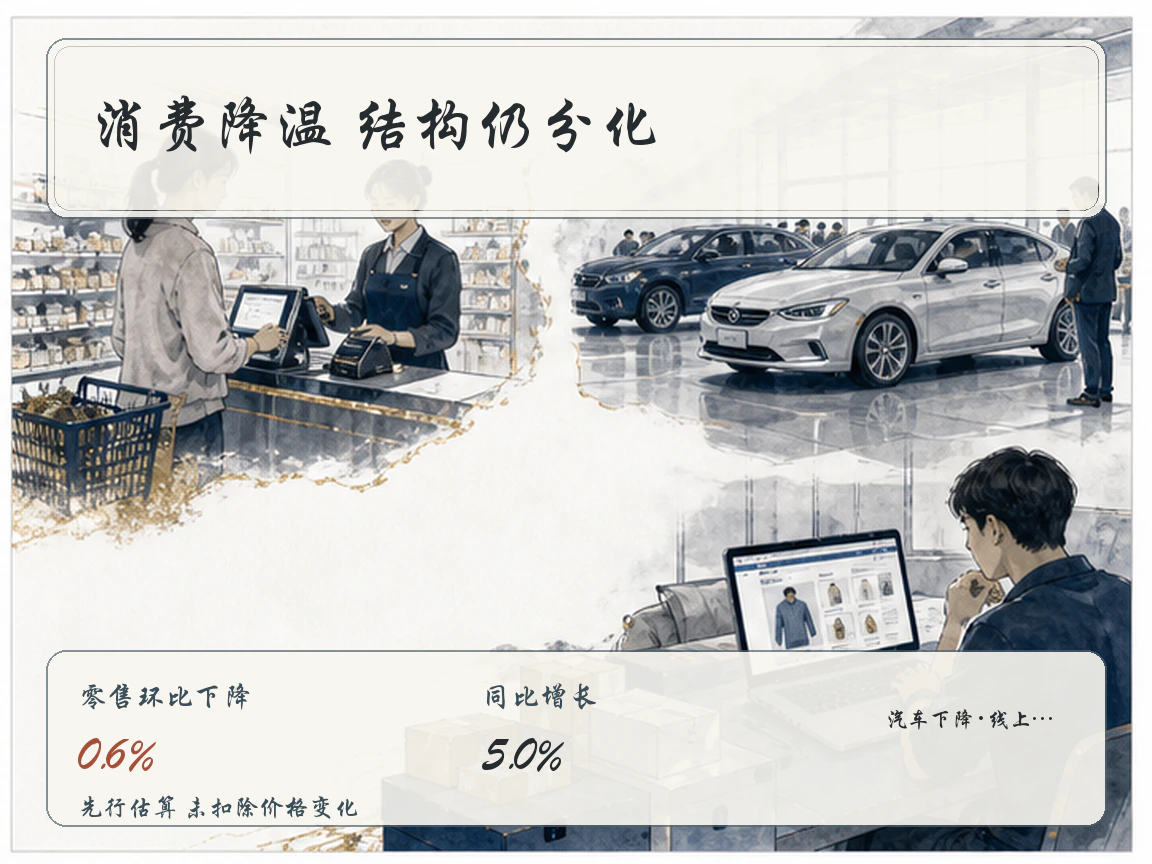
Census Bureau data put seasonally adjusted July retail and food-service sales at $763.6 billion, down 0.6% monthly but up 5.0% annually; May–July combined grew 6.3% year on year. It was the first monthly fall in nine months and substantially weaker than expectations for modest expansion.
Composition matters more than the aggregate fall. Autos and parts declined 1.8% and nonstore online sales 2.2%, the principal drags. Excluding autos, sales fell 0.3%; excluding autos and gasoline, 0.2%. Food services still grew 0.5%, while clothing and personal-care products rose 1.9% and 0.7%. Purchasing power was not collapsing indiscriminately: weaker durables coexisted with modest support from in-person services.
The preliminary estimate samples about 4,800 businesses and is not price-adjusted, so it cannot directly equal a decline in real consumption volume. A more reasonable interpretation is technical payback after tax-refund stimulus and midyear online promotions pulled durable demand forward. Actual resilience needs cross-checking against employment, real disposable income, core PCE and company interim results.
Slower consumption first affects revenue in general retail, digital advertising, trunk logistics and discretionary sectors. If services and labor remain firm, sector rotation can absorb the pressure. Only if weakness spreads into dining, jobs and core incomes will one month's fluctuation be repriced as a sustained slowdown.
Bonds Do Not Confirm Easing; They Demand More Term Compensation
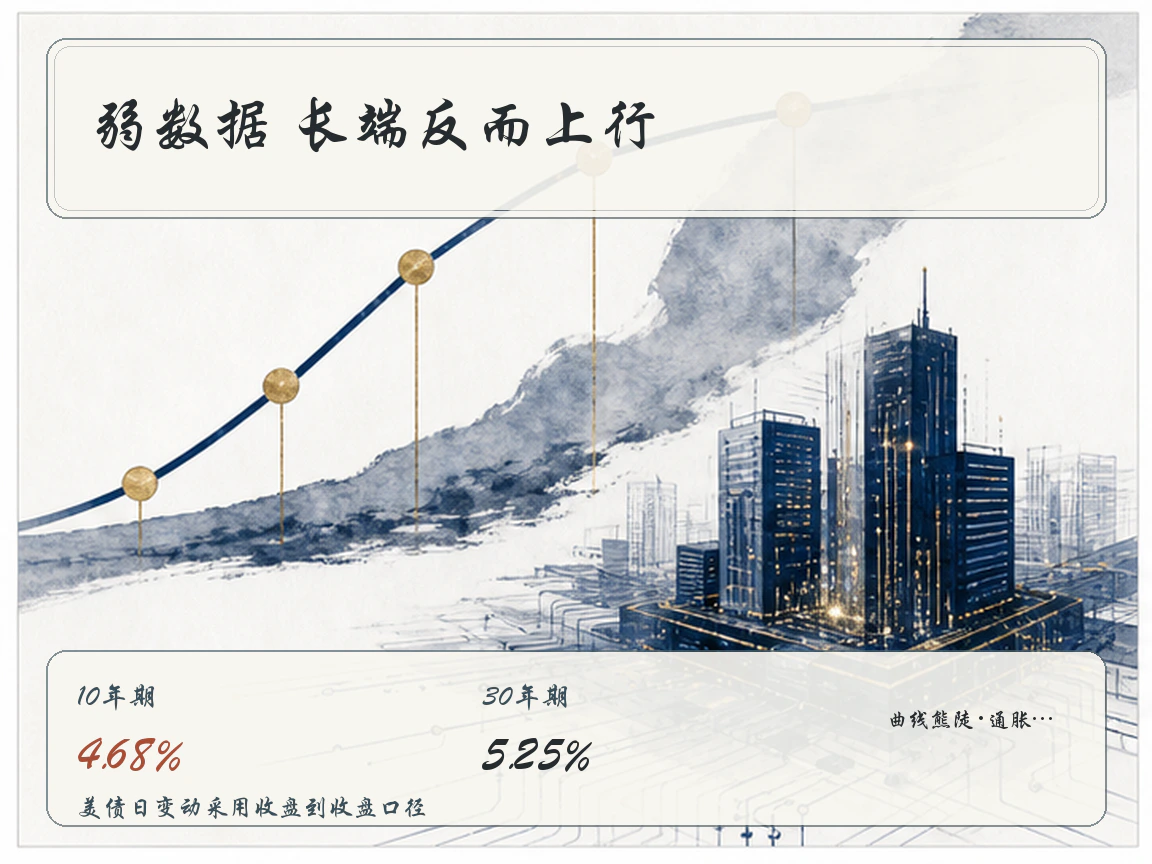
The official Treasury curve showed two-year yields up 2 bp to 4.17%, five-year up 4 bp to 4.36%, 10-year up 5 bp to 4.68%, and 30-year up 4 bp to 5.25%. The 10-year/two-year spread widened to 51 bp, producing bear steepening despite soft data.
If bonds were trading only slower growth and rate cuts, long yields should have fallen. Their rise reflects investors demanding more compensation for sticky inflation, Treasury supply and the term premium associated with fiscal expansion. One session cannot quantitatively isolate the dominant factor, but higher yields clearly contradict a simple direct path from weak data to lower risk-free rates.
Inflation compensation corroborated this. Five- and 10-year breakevens each rose 3 bp to 2.24% and 2.27%; five-year/five-year forward compensation reached 2.30%. These market-implied expectations did not fall with one weak retail month, instead showing resilience amid persistent geopolitical oil premiums and heavy issuance.
For expensive equities, high long benchmark rates matter more than daily index falls below 0.2%. A 10-year yield at 4.68% fixes a high floor under discount rates. The further into the future growth stocks' earnings lie, the more their discount-rate sensitivity grows nonlinearly. Bad data can become good news only when weaker demand simultaneously delivers lower inflation and lower long risk-free rates.
Behind Low Headline Volatility, Internal Pricing Diverges
On August 14 the S&P 500 eased to 7,785.76, Nasdaq 100 closed at 30,046.14 and Dow at 53,732.41. Declines were tiny and VIX fell 2.60%. Most desks saw routine consolidation after record highs, rather than systemic deleveraging.
Underlying structure was diverging. Russell 2000 small caps rose 0.51% against large-cap declines. This can indicate remaining risk appetite betting on weak data forcing near-term easing, or attempts to diversify holdings. But small caps depend more on marginal financing costs and domestic demand than major technology firms, so one day's bounce cannot establish the disappearance of growth concerns.
A low, stable VIX can also mislead. It measures at-the-money implied volatility in S&P 500 options, and offsetting heavyweight moves can conceal individual-stock fractures. It cannot fully price credit spreads, quarterly earnings divergence or geopolitical tails. Low VIX alongside rising oil, gold and long yields more plausibly means macro risks are distributed across assets rather than eliminated.
Key tests are whether small-cap strength is accompanied by narrower corporate credit spreads and whether earnings expectations withstand slower consumption and higher long borrowing costs. If broad indexes move from sideways trading to a struggle to hold levels while credit and earnings downgrades develop first, the calm can break quickly.
Oil and Gold Rise Together: Nominal Risks Remain
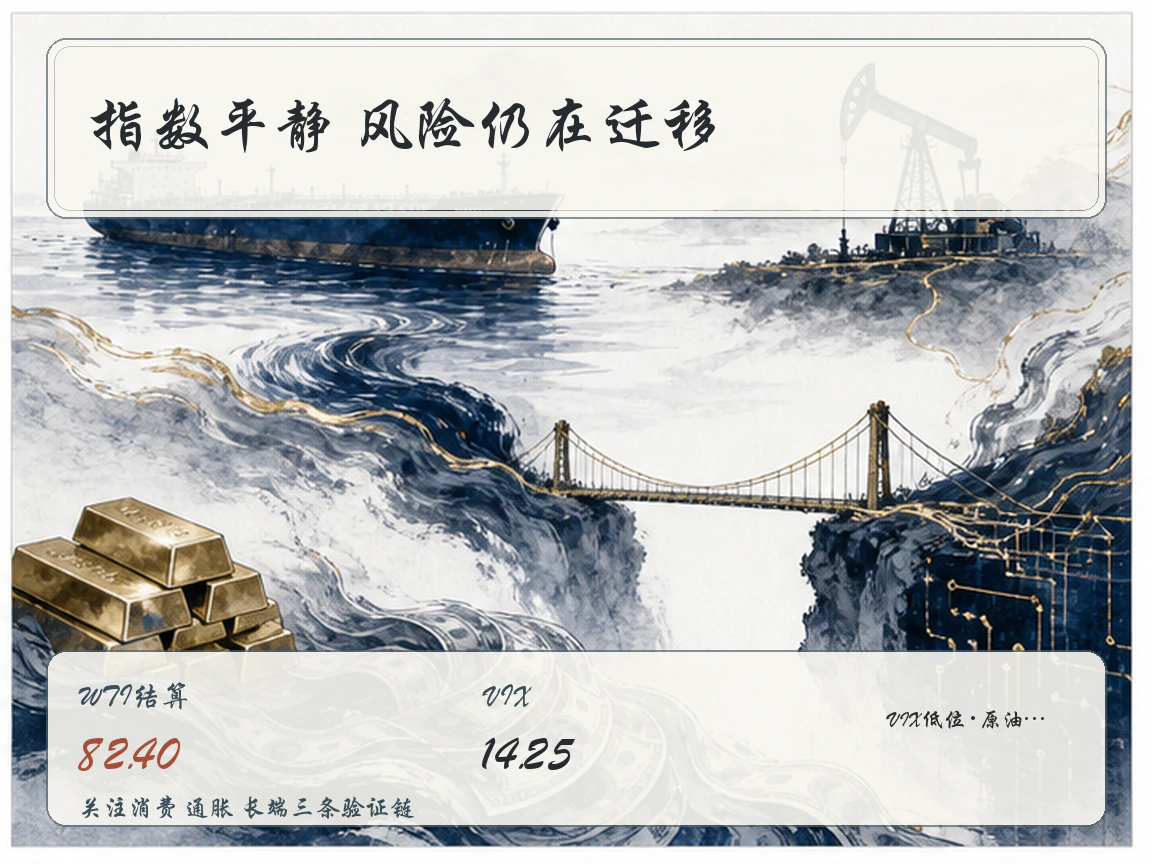
Commodities and FX showed clear macro hedging. September 2026 WTI settled at $82.40 a barrel, up $1.15 or 1.42%; October Brent consolidated high near $88.52. The dollar index fell 0.33% to 99.636, while December COMEX gold rose 0.38% to $4,437.3 an ounce.
A weaker dollar supports commodities, but oil's strength is more deeply tied to supply, shipping premiums and Middle Eastern geopolitics. Oil is also a transmission hub for global expectations: persistently high tanker insurance and freight costs spread through fuels, industrial intermediates and inflation expectations, eroding profits and closing room for long yields to fall.
Gold rising with Treasury yields is not a conventional one-way real-rate trade, but cross-asset hedging. Investors keep paying to protect against lost purchasing power, US fiscal expansion and nonlinear geopolitical risks. Resilient oil and stronger gold show nominal risks have not disappeared with slower consumption, restricting monetary easing and undermining support for equity multiple expansion.
No Global Risk Stampede, but Credit Spreads Offer Little Defense
Safe-haven sentiment did not spread across regions. Nikkei 225 rose 0.55%, Hang Seng 0.33% and KOSPI 0.21%. The euro rose 0.45% against the dollar and USD/JPY slipped 0.21%. US consolidation remained an internal pricing adjustment, without forced liquidation across countries and assets.
Credit also showed no selling. FRED data through August 13 put US high-yield OAS at 2.71 percentage points and investment-grade spreads at 0.79, both historically low. Despite a one-day lag, this showed no sudden blockage in corporate issuance or credit liquidity.
Very narrow spreads and suppressed VIX cut both ways. They confirm this is not currently a recession trade, but leave almost no safety cushion. When markets pay very little for default and volatility protection, renewed inflation, unexpected earnings downgrades or longer-lasting restrictive rates can trigger abrupt nonlinear repricing. This is not a moment for wholesale retreat, but demands on balance-sheet strength, free cash flow and pricing power are exceptionally high.
Monitoring Framework: Three Tests beyond the Low-Volatility Surface
Rather than focus on a few index points, the next stage requires three intertwined tests:
First, final-demand transmission. Is July's retail weakness normal mean reversion after promotions pulled durables forward, or an early sign of deeper purchasing-power damage? Stable services, wages and claims allow normalization to explain it. Spread into dining, recreation, broad employment and disposable income would make systematic earnings downgrades unavoidable.
Second, costs and inflation compensation. Whether geopolitical premiums, tanker costs and producer disruptions reach breakevens determines whether weak growth can deliver low rates. Peaking oil and anchored inflation could open valuation relief through lower long yields. Persistent energy strength would instead turn resistance to policy cuts into a capital-market burden.
Third, duration premiums and credit spreads. If 10- and 30-year yields stay high despite soft data amid heavy issuance, fiscal-driven term premiums are taking over long-end pricing. If high yields coincide with widening high-yield spreads, calm indexes may conceal substantive credit tightening and risk spillover.
August 14 was neither panicked recession pricing nor a smooth easing trade. It was a subtler dilemma: demand began weakening as capital costs rose; indexes stayed calm while commodities and gold moved beneath the surface. For US equities to break through high-level resistance into another expansion, the key is not hoping weak data force cuts, but whether slower growth, lower inflation and falling long yields finally move together.


