Understanding the Federal Reserve, Article 9 of 20
New England combines one of America's densest concentrations of leading universities, medical institutions, asset managers and life-science clusters with an exceptionally highly educated workforce. Yet businesses in this innovation hub face a seemingly ordinary but stubborn constraint: extremely inelastic housing supply, high living costs and intensifying population aging. Employees shoulder heavy housing burdens and firms repeatedly find expansion limited by labor shortages. Persistent wage pressure here cannot be explained simply by excessive aggregate demand.
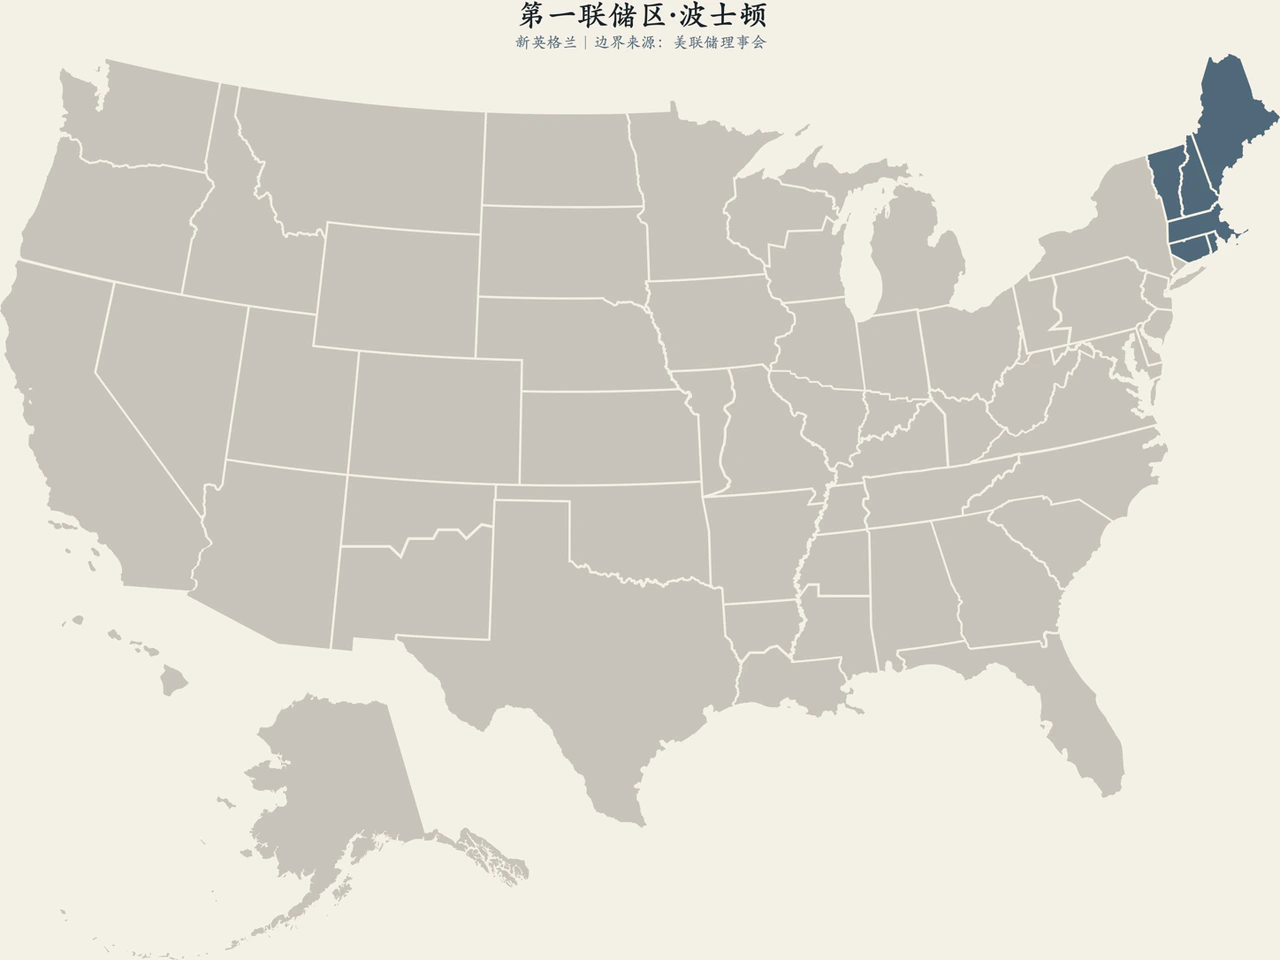
The Boston Fed's statutory district covers all of Maine, Massachusetts, New Hampshire, Rhode Island and Vermont, plus Connecticut excluding Fairfield County. Fairfield belongs to the Second District, New York, because of its close commercial and commuting ties with that metropolitan area. These century-old boundaries follow economic hinterlands rather than administrative lines alone.
1. New England Is a Composite of Multiple Cycles
Greater Boston Is Young and Ambitious; Northern States Are Deeply Aged
Greater Boston's universities, research institutions and venture capital place it at the forefront of global education, health care, biopharmaceuticals and modern finance. Much of Maine, Vermont and New Hampshire is sparsely populated and heavily aged, relying on forestry, traditional manufacturing, tourism and wellness, and local small firms. Southern Rhode Island and Connecticut have established precision manufacturing, insurance and actuarial services, commercial health care and defense industries.
A nationwide period of restrictive rates affects these areas very differently. Tightening first restrains early-stage venture capital, startup valuations and core commercial real estate around Boston. Higher mortgage costs then freeze existing-home turnover and buying demand across the states. Slower discretionary consumption directly hits tourism services in Maine and Vermont. Universities and major hospitals have more cyclically resilient hiring demand, but still face tighter public funding, constrained tuition growth and difficulty recruiting specialized care workers.
The First District is among the few regional Reserve Banks with no branches, operating from its Boston headquarters. That does not confine its perspective to Greater Boston. Business contacts, routine microeconomic surveys, community-development research and state-level data cover New England widely. One central task is to prevent the core metropolis from obscuring the district's heterogeneous reality.
When Inelastic Housing Supply Becomes a Macroeconomic Employment Bottleneck
Employers' reported hiring difficulties may appear to reflect inadequate wage offers, but underlying barriers combine skill gaps, commuting limits, family-care burdens and housing affordability. Stringent zoning, lengthy planning approvals, high environmental and construction costs, and New England's geography nearly lock down the elasticity of new housing supply. Interest-rate policy can reduce borrowing demand but cannot create developable land.
As central-city prices and rents rise, ordinary skilled workers must endure extreme commutes or leave. Firms competing within a limited local talent pool are forced to keep raising wages.
This mechanism ultimately confronts both maximum employment and price stability. Faster wages need not mean overheating demand; housing constraints can raise workers' reservation wages and firms' hiring costs. A central bank that mechanically attributes high wage growth to excessive demand and tightens further risks harming activity while missing the structural cause. Persistent supply bottlenecks also cannot justify allowing a wage-price spiral. The First District projects the Fed's dual-mandate tension onto the physical constraints of daily life.
2. How Regional Problems Reach Washington's Policy Table
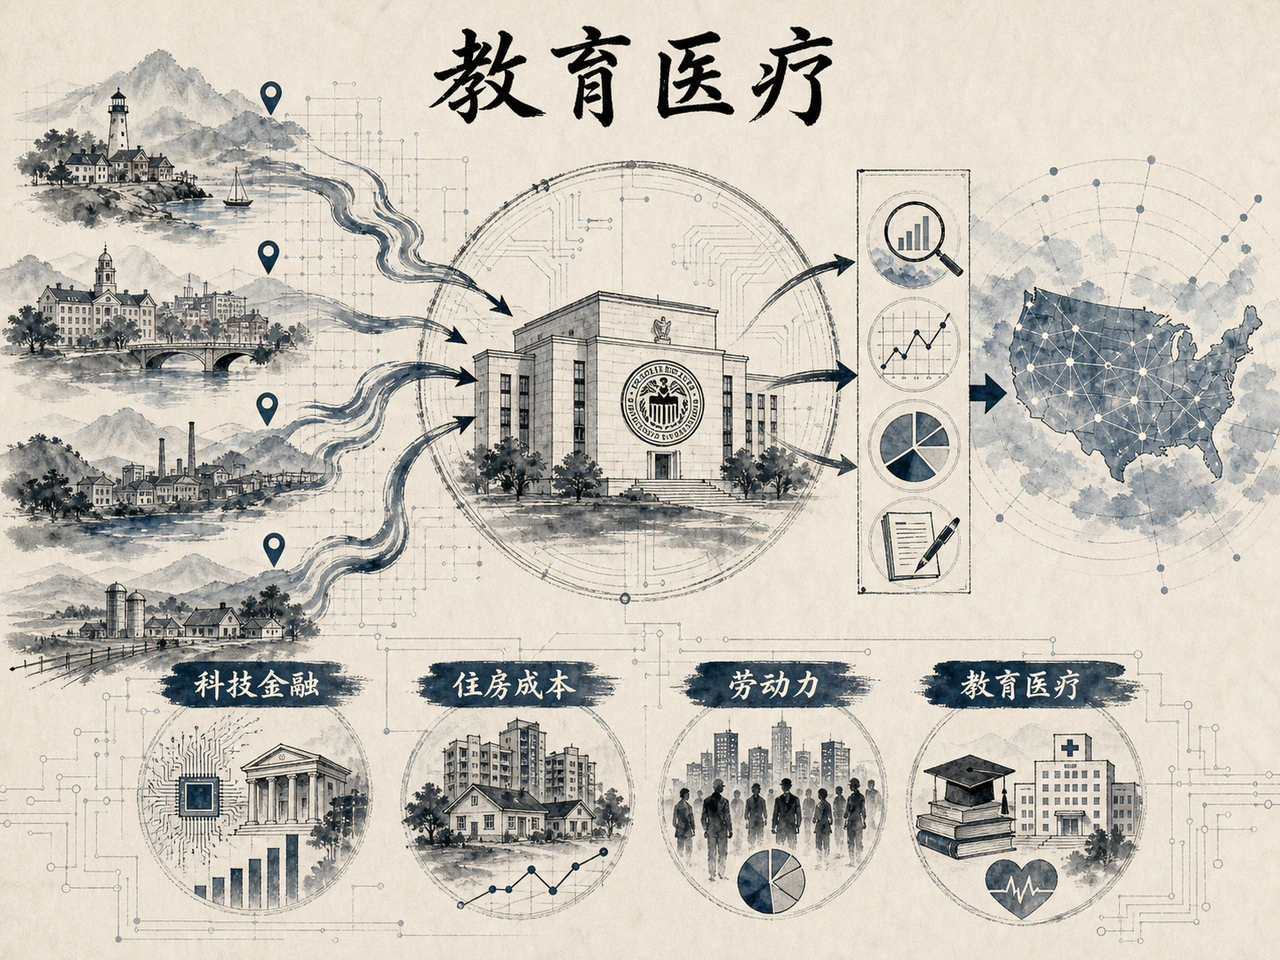
Macroeconomic Research, Regional Public Policy and Payment Innovation Have Distinct Roles
The Boston Fed's research team has long worked at the frontier of monetary transmission, labor economics, inflation expectations and financial-market frictions. Its New England Public Policy Center focuses more on state and county fiscal gaps, land and housing policy, and regional migration, translating academic models into practical regional discussion. The two paths serve different audiences but share a central question: how do national tightening and easing affect local economic reality?
The bank also conducts forward-looking research into payments and financial infrastructure. Digital-currency prototypes with MIT, such as Project Hamilton, are technical feasibility and mechanism proofs of concept, not evidence of an official system-wide Fed implementation plan. Regional research interests are informative but must not be presented as established FOMC policy.
Community development focuses on low-income households, new small businesses and regional financial institutions. Even affluent New England has substantial inequality, segregation and urban–rural divides. Strong average wages cannot erase low-income households' difficulties with housing, small loans and public transport access. These details may be hard to express in quarterly GDP, but determine whether ordinary workers can actually access jobs.
Understanding Susan Collins' Framework beyond Hawk and Dove Labels
Susan M. Collins became Boston Fed president in July 2022. Under the 2026 FOMC rotation she is not a voting member, but still participates fully in every policy debate and submits SEP projections. Her recent public analysis recognizes economic resilience to external tightening shocks while repeatedly warning that disinflation is nonlinear, especially when recurring supply disturbances create second-round risks.
Permanently labeling an empirically grounded academic policymaker a hawk or dove has little analytical value. If unavoidable supply constraints keep inflation high while labor-market slack begins to emerge, the balance of risks changes dynamically. More useful analysis tracks how she assesses the breadth of inflation, genuine labor slack, changes in firms' pricing power and overall financial conditions.
3. How Professional Investors Should Read the First District
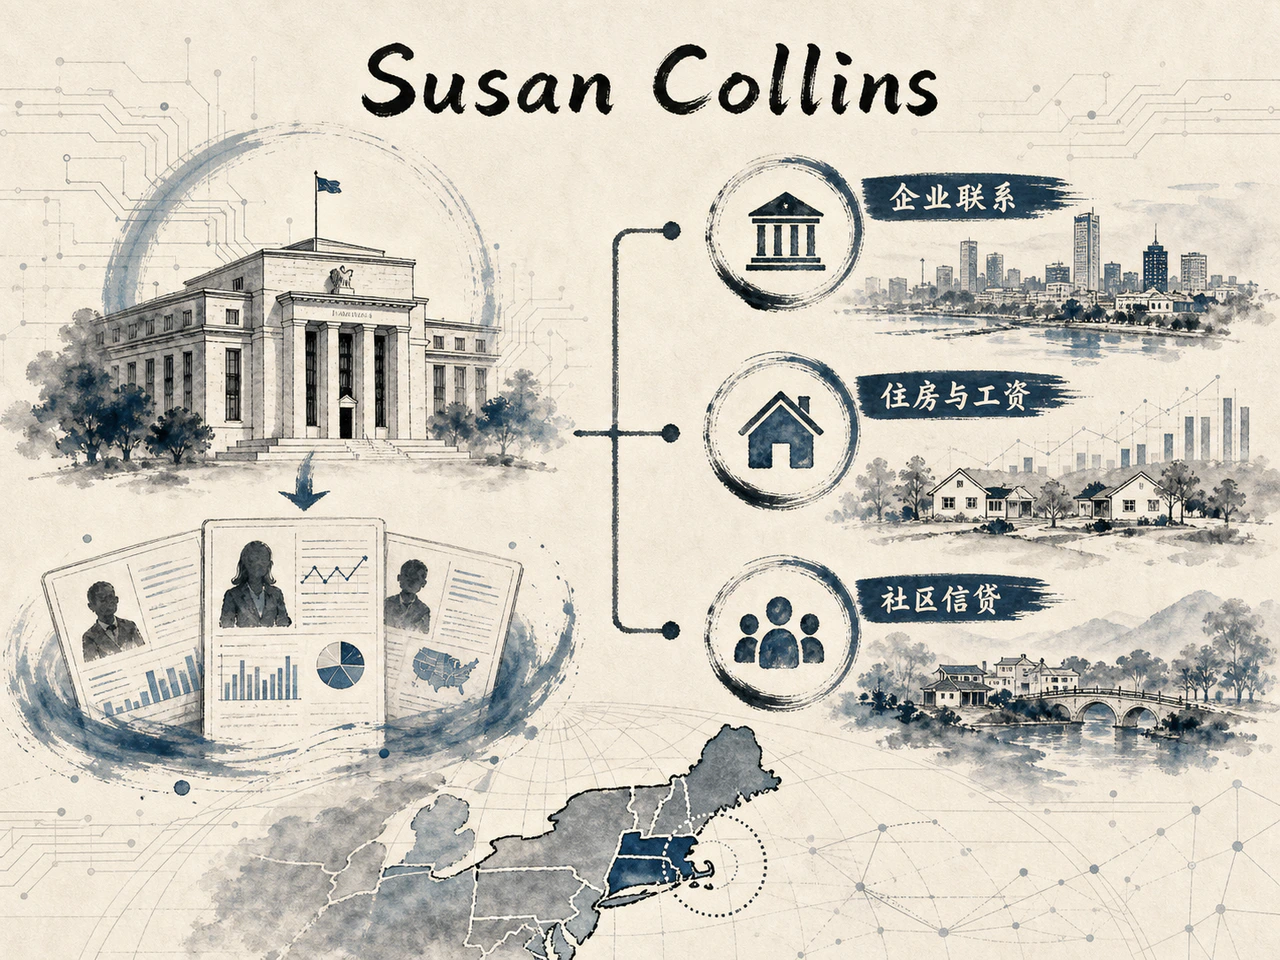
The Data Network Explains Structural Frictions Rather Than Replacing National Trends
The Boston Fed's New England Economic Indicators system compiles employment, unemployment, income, housing permits and migration across the six states. It is a valuable database for differences in state cycles and local frictions. Its purpose is not to provide an advance signal of a sudden national trading shift, but to explain why the same benchmark rate produces very different tolerance and lags across economic structures.
Interpretation requires at least three comparisons: Greater Boston versus smaller metros; mature coastal urban areas versus inland mountain and nonmetropolitan regions; and high-value innovation dependent on young intellectual capital versus aging traditional manufacturing. A low district-wide unemployment average can conceal shrinking labor supply in peripheral counties alongside premium bidding for highly skilled workers at central professional institutions.
Three Core Monitoring Themes
Investors following real-economy liquidity and macro cycles should track three themes in the Boston district:
- Housing permits, effective rents and net interstate migration: the most direct window into easing labor-supply constraints, shaping core-area wage floors and the persistence of services inflation;
- Leading universities' R&D spending, clinical institutions' cash flows and life-science venture capital spending: a gauge of how knowledge-intensive assets translate into total factor productivity and broad employment;
- Small-business lending spreads, community-bank funding costs and default rates: a test of restrictive rates' transmission through New England credit intermediation and whether tightening is harming the real economy's outer reaches.
These themes respectively anchor supply elasticity, productivity momentum and credit health.
The Boston Fed's contribution to the macro framework is clear: high income, educational attainment and concentrated innovation capital do not eliminate systemic vulnerabilities. Restrictive housing rules and aging demographics can magnify local physical constraints into bottlenecks in wages, prices and potential growth. The institutional purpose of retaining 12 geographically dispersed Reserve Banks is precisely to ensure that mechanisms missed by a single national average keep reaching the highest level of monetary decision-making.