Understanding the Federal Reserve, Part 4/20
Is the Fed a government agency or a profit machine controlled by private bankers?
Election years and painful monetary tightening repeatedly bring this question back through popular conspiracy theories. The black-and-white framing starts from a false premise. Treating the Fed as an ordinary commercial bank or a conventional cabinet department leads to fundamentally wrong conclusions.
From its inception, the system was a compromise between American federalism and repeated financial panics. Washington's Board of Governors is an independent federal agency. The twelve regional Reserve Banks are special legal entities created by Congress with public missions and regional private-law forms. The FOMC, determining the global cost-of-funds anchor, combines these two forces within a statutory framework.
Fed independence is not an extralegal privilege above sovereignty. It is operational autonomy within congressional law and political checks. Appointments, stock characteristics and oversight boundaries reveal who ultimately determines dollar policy.
1. Power comes from Congress; appointments deliberately extend the time horizon
Independence still begins with an act of Congress
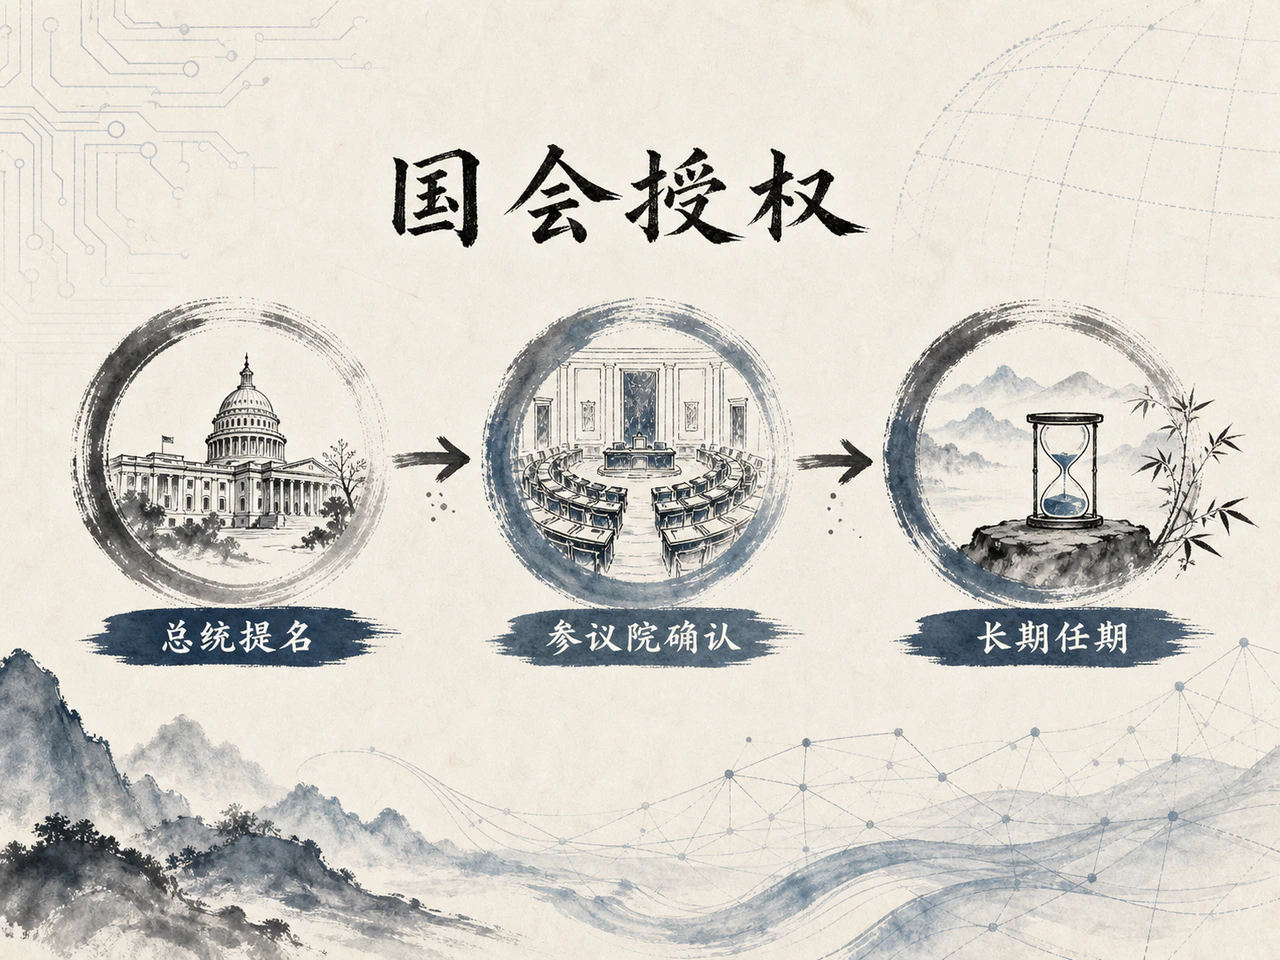
Article I, Section 8 of the Constitution gives Congress power to coin money and regulate its value. All Fed statutory powers derive from the Federal Reserve Act of 1913 and subsequent amendments.
Congress sets the dual mandate of maximum employment and price stability, divides authority between the Board and Reserve Banks, and limits emergency assistance, including Section 13(3), and supervision. It can legislate new tools or remove powers. Independence is instrumental rather than goal-setting: the Fed cannot set national strategic objectives, but can decide the timing of hikes, cuts and balance-sheet adjustments under its legal authorization.
The Board has seven governors, nominated by the president and confirmed after Senate hearings. To protect monetary discipline from short-term partisan politics, statutory terms are fourteen years, staggered so one expires every two years.
Fourteen years spans three and a half presidential terms. Ordinarily, even a reelected president cannot replace the whole Board quickly after one election. Chair and vice-chair leadership terms are four years, separately nominated and confirmed and renewable where eligible, but must fit within their governor terms.
In practice, resignations, academic returns, industry moves and politics often shorten service well below fourteen years, typically to around six to eight, giving the White House vacancies to fill. The staggered statutory structure nevertheless remains a first defense against capture by a single administration.
The chair is not an autocratic corporate chairman. In FOMC discussions of rates and the balance sheet, the chair has only one vote among nineteen participants, cannot bypass the Committee to impose open-market policy, and cannot direct votes by legally independent regional presidents. Influence chiefly comes from agenda-setting, consensus-building and institutional authority in public communication, not unilateral administrative power.
Regional presidents are neither presidential nominees nor simply shareholders' choices
Appointments at the twelve regional banks balance local autonomy with Washington oversight.
Each bank has nine directors, divided strictly into three each in Classes A, B and C:
- Class A: elected by member commercial banks in the district to represent banking;
- Class B: also elected by member banks, but legally required to come from commerce, agriculture, industry, labor or consumer services rather than banking, representing broad real-economy interests;
- Class C: appointed directly by the Board to represent the public. Regional board chairs and deputy chairs must be Class C directors.
The crucial safeguard is presidential selection. Many assume commercial banks can select compliant regional presidents through their capital contributions. Under the current framework and strengthened Dodd-Frank Section 113 restrictions, however, Class A directors representing banking and certain directors with banking affiliations are legally excluded from voting on presidents and first vice presidents.
Nonbank Class B and C directors form the search committee and recruit publicly. Their preferred choice must go to Washington's Board for compliance review and final approval. The Board has a veto and evaluates performance in the common five-year reappointment cycle. This prevents direct White House placement of political allies and guards against capture by Wall Street or local financial interests.
2. Member banks own stock, but are not shareholders in the ordinary sense
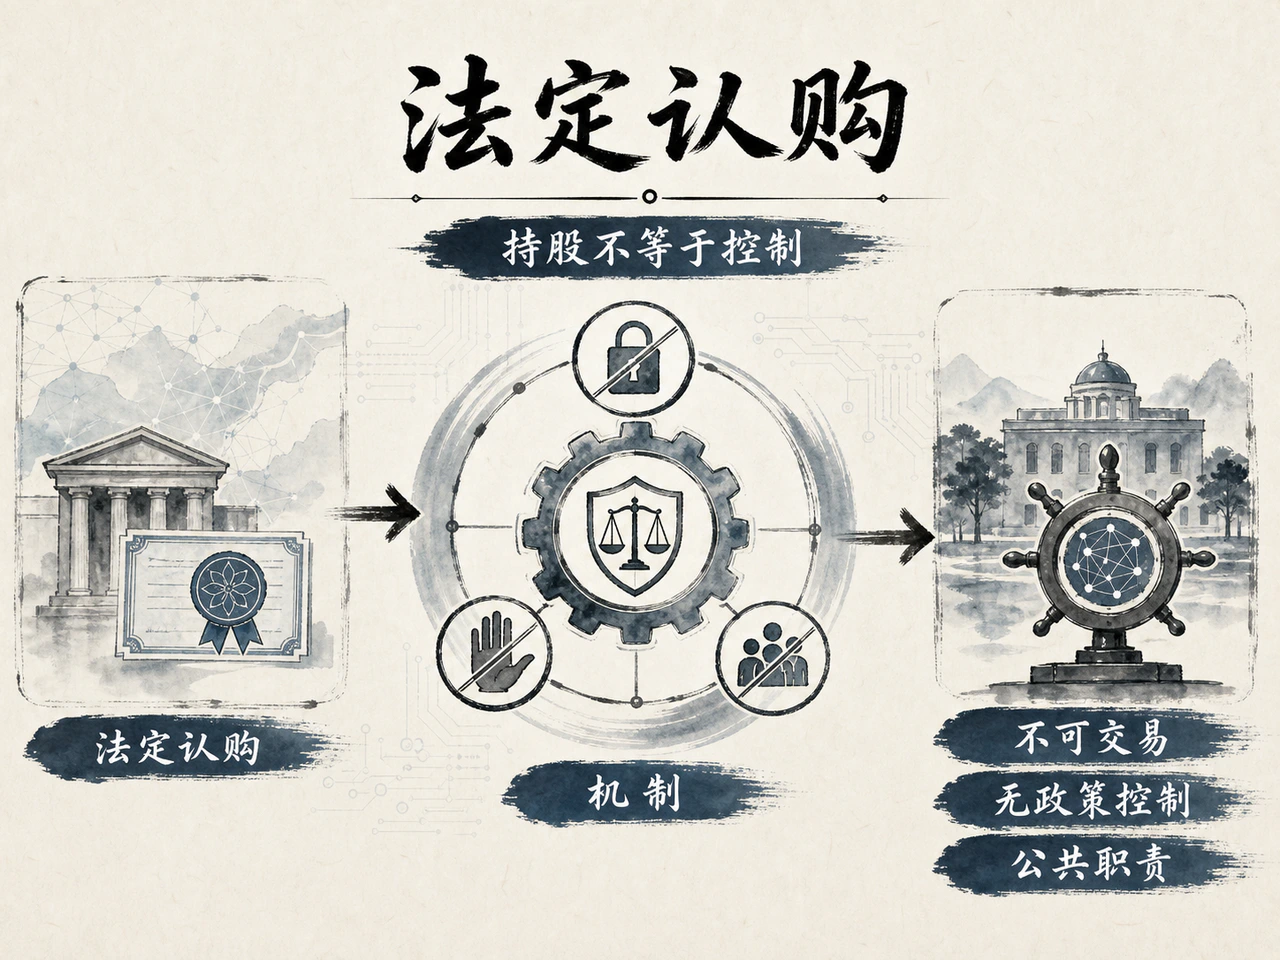
The stock resembles a legally constrained membership ticket
Commercial banks own Fed stock, therefore the Fed is a private bank: this is among the most widespread and misleading claims.
Member banks—all nationally chartered banks must join, while state-chartered banks may apply voluntarily—must indeed subscribe to stock in their regional bank in proportion to their own capital and surplus. But this stock lacks the defining features of ordinary corporate equity:
- No transfer or trading: the stock cannot be traded publicly, sold, given away or pledged as collateral. On failure or withdrawal, it is returned and canceled at par, leaving no premium realization or capital gain.
- No control or residual claim: votes do not scale linearly with holdings. Small and large banks vote in separate election groups. No amount of capital can confer control of the board or demand a monetary-policy preference from the FOMC.
- Dividends strictly capped by statute: Reserve Banks pay a statutory dividend, historically fixed at 6%. After the 2015 FAST Act, banks with assets above $10 billion receive the lower of 6% and the latest 10-year Treasury auction yield.
This arose from the 1913 compromise: Congress wanted to bind dispersed banks' capital into a common clearing and lender-of-last-resort network while preventing private bankers from appropriating sovereign monetary power. Banks fund the system's basic operating foundation in return for statutory access to central-bank settlement and the discount window, without sharing public-power privileges.
Calling regional banks purely private companies ignores their statutory public goals and Washington's veto. Treating them as ordinary agencies fails to explain their distinctive governance and private-law employment. Special statutory legal entities accurately describes the hybrid.
No annual appropriation, but accountability for every public dollar
A central financial characteristic is complete independence from Congress's annual operating-appropriation process.
This funding design prevents executive and legislative use of the purse to coerce monetary policy. Revenue chiefly comes from interest on Treasuries and agency MBS in the System Open Market Account (SOMA), plus fees for payment and settlement services.
In normal years, after operating costs, capped statutory dividends and required surplus retention, almost all net earnings—often tens or hundreds of billions of dollars annually—are remitted to the U.S. Treasury, directly supporting public finances.
In aggressive hiking cycles such as 2022-2024, high interest on reserve balances (IORB) and overnight reverse repos (ON RRP), against fixed income on existing low-yielding intermediate and long assets, can temporarily invert income and expense and create operating losses.
The Fed records these losses as a deferred asset. It does not seek taxpayer rescue from Congress or enter ordinary corporate insolvency and liquidation. When lower rates restore profitability, earnings first offset the accumulated deferred asset; regular Treasury remittances resume only after it is cleared. This accounting again shows the fundamental difference between a sovereign fiat-money creator and a private company responsible for its own profits and losses.
No appropriations do not mean closed accounts. Every expenditure extends the statutory public balance sheet and faces multiple internal and external independent reviews.
3. Independence addresses short-term pressure; accountability limits long-term power
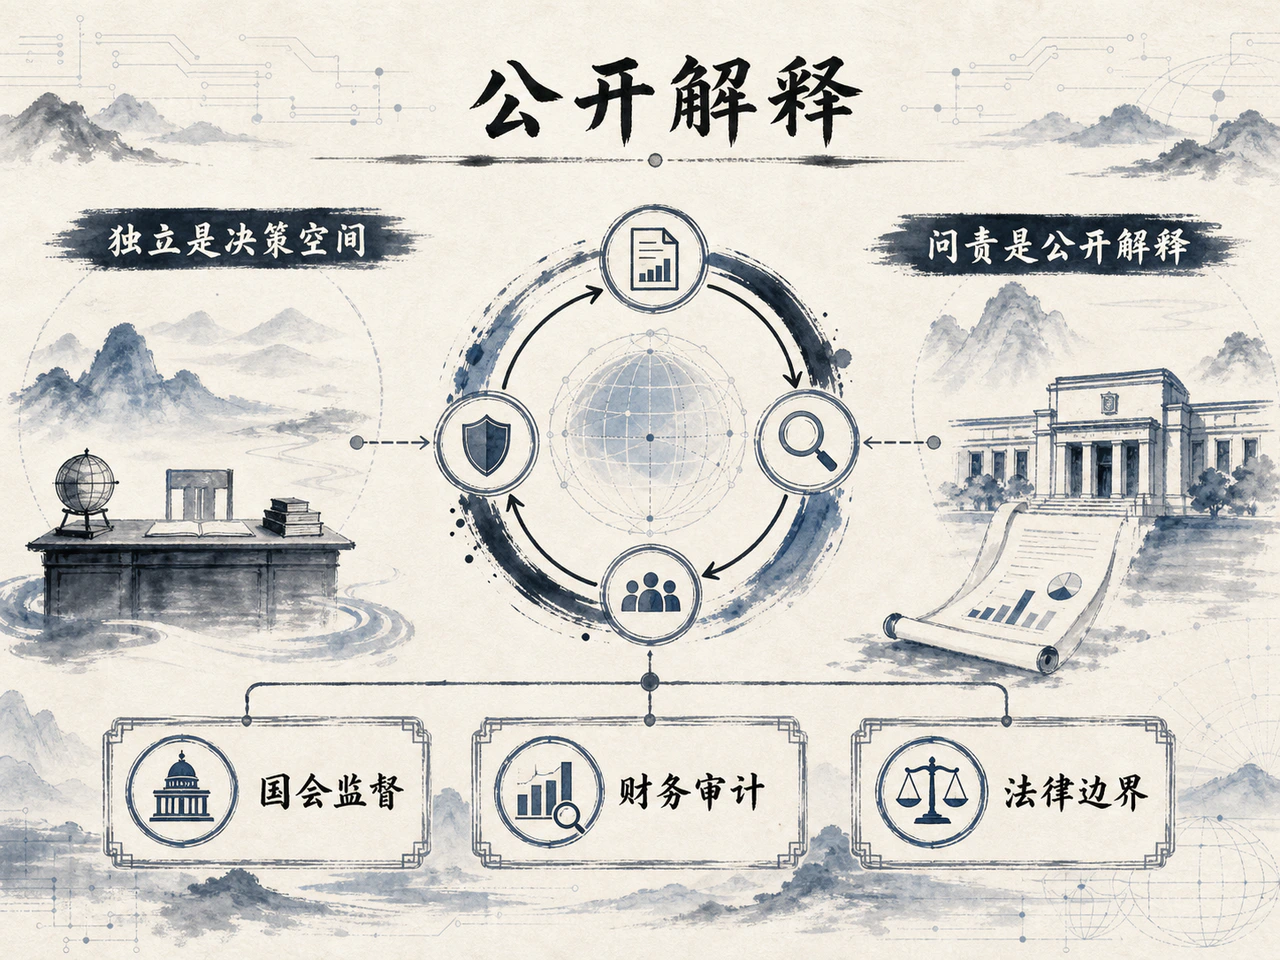
The claim that the Fed is unaudited confuses two kinds of oversight
The inflammatory online slogan Audit the Fed implies an extralegal vacuum without scrutiny. It confuses financial-compliance auditing with interference in monetary policy.
The system has two distinct oversight tracks with separate roles:
First: comprehensive, routine financial and operational audits.
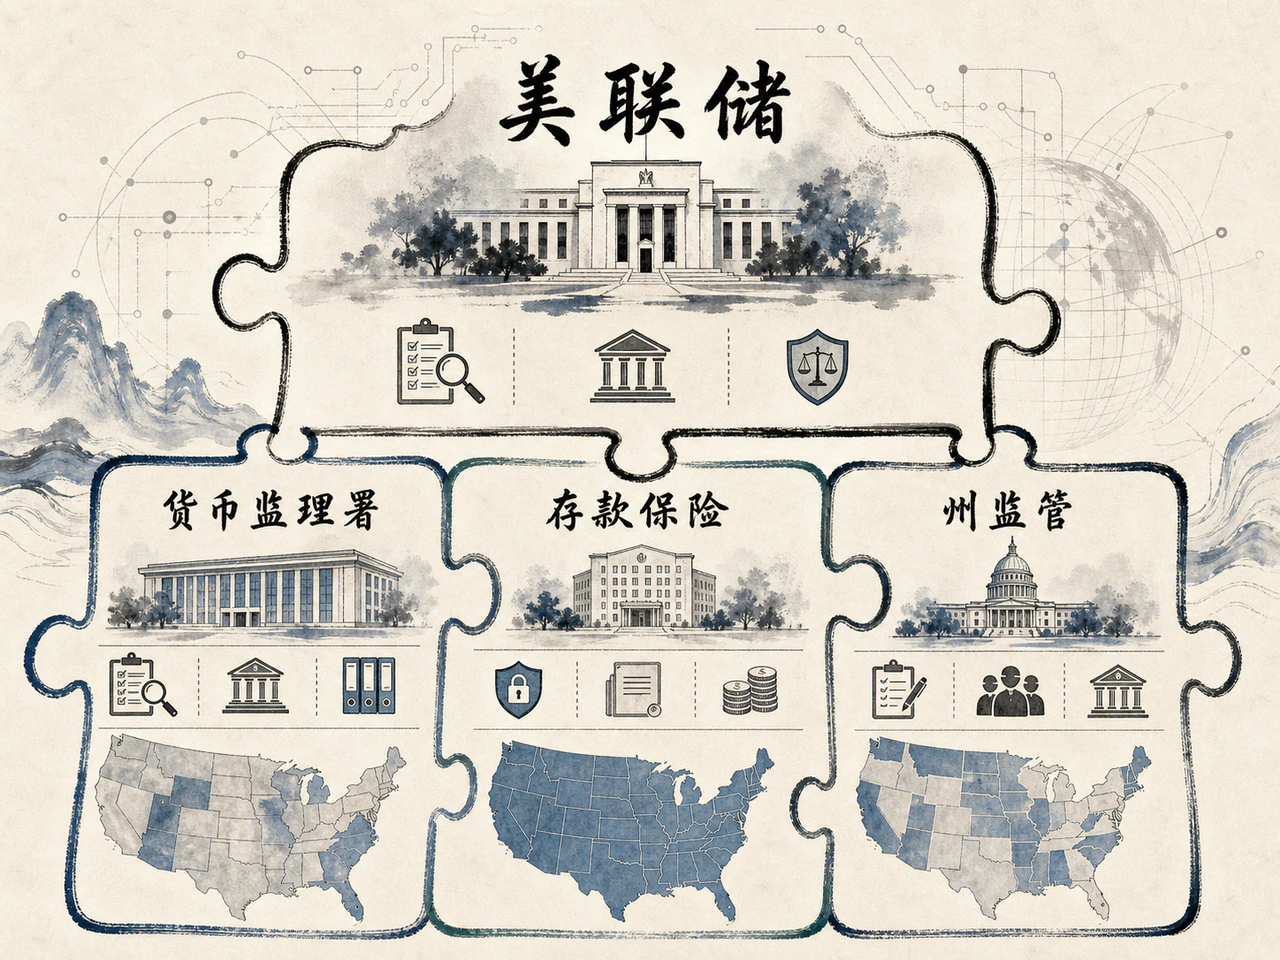
The consolidated financial statements of the Board and twelve Reserve Banks undergo mandatory annual external audits by leading independent accounting firms, with full reports public. The GAO, Congress's investigative and audit arm, conducts recurring reviews of administrative spending, IT security, emergency-program compliance and supervisory procedures. The Board also has an independent Office of Inspector General (OIG), reporting to Congress, investigating corruption, conflicts and compliance failings.
Second: independent policy space with subsequent accountability.
The legal restriction is the firewall established in the Federal Banking Agency Audit Act of 1978: GAO may not directly audit FOMC policy discussions, prospective rate decisions, specific open-market instructions or monetary transactions with foreign central banks and international organizations.
Congress's rationale was forward-looking. Allowing investigators to obtain closed deliberations after each rate adjustment under an administrative-audit label would turn each decision into a political revote by legislators. The boundary protects monetary decisions from short-term partisan capture rather than hiding financial accounts.
For policy accountability, a separate demanding transparency system serves the public:
- Twice-yearly, hours-long public chair testimony and questioning before House and Senate banking and financial committees, accompanying the semiannual Monetary Policy Report;
- Statements, implementation notes and a live chair press conference immediately after each policy meeting;
- Detailed minutes released three weeks later, running to tens of thousands of words and presenting internal debate;
- Quarterly SEP projections and anonymous dots;
- Full verbatim closed-meeting transcripts released to the world after five years.
Financial audits ask whether funds were misused or procedures breached; policy accountability asks whether decisions honored statutory objectives and the public trust. They cannot and should not be conflated.
Political influence persists, but cannot directly dictate a rate decision
Operational independence does not put policymakers in a vacuum. Political influence operates persistently and systematically on a broader scale.
Presidential nominations and Senate confirmations reshape intellectual schools and hawkish or dovish inclinations over years. Congress can redefine powers and mandates through law. Tough hearings affect credibility. Fiscal expansion, tariffs, issuance and geopolitical strategy directly shape the economy and inflation the Fed confronts.
Politics is everywhere, but the system blocks the most dangerous step: a president cannot sign an executive order requiring a 50-basis-point cut tomorrow morning.
Operational independence addresses the time-inconsistency problem established in modern economics. Elections encourage preelection stimulus and artificial prosperity, leaving inflation, bubbles and debt collapse to successors or the public. Independence is an institutional safety line against short-term instincts.
Technocratic autonomy has risks too. Unchecked experts can lapse into model-driven groupthink, overlook monetary distribution effects on poorer households or obscure value judgments in jargon. Independence is no privilege certificate; it is a fragile public contract, repeatedly justified through exceptional transparency, rigorous analysis and honest constitutional and public accountability.
So who controls the Fed?
No single president, New York financial group or chair. Congress sets the legal track; the White House and Senate select key drivers; the Board governs operations; FOMC collective votes steer policy; twelve regional banks provide real-economy intelligence; and the public and markets assess results through hearings and disclosures.
The layered structure inevitably creates administrative friction and slow compromise. That is precisely its deepest purpose: professional expertise, regional interests and democratic politics check one another so no party can fully appropriate the country's monetary privilege.