Understanding the Federal Reserve, Part 7/20
Macro observers often encounter apparent anomalies: the FOMC cuts rates but 10-year Treasury yields rise, or large benchmark cuts barely ease corporate spreads and mortgage costs. Such divergence is common and does not indicate system failure. The closed Washington vote determines only a very short-term overnight target range; it neither directly sets long-asset discount rates nor prices every credit contract.
Policy must traverse two different stages to change real resource allocation. Implementation uses the central-bank balance sheet and administered rates to anchor dispersed secured and unsecured overnight markets within the target range. Transmission carries short-funding changes through term premiums, credit spreads, bank balance-sheet constraints, exchange rates and asset valuations into investment and consumption. The first is precise trading-desk technique; the second is embedded in complex intermediaries and expectations, with long, variable lags and potentially powerful offsets from fundamentals and psychology.
1. How the target range becomes actual overnight rates
What the federal funds market actually lends
Federal funds are not abstract fiscal provisions or banknotes, but required and excess reserve deposits at Reserve Banks held by eligible institutions. Eligible financial firms, mainly commercial banks and GSEs such as Fannie Mae and Freddie Mac, borrow and lend overnight reserve positions without collateral to balance asymmetric end-of-day settlements. The New York Fed publishes the effective federal funds rate (EFFR), a weighted median of actual large transactions each trading day.
Before the 2008 crisis, banks held limited reserves under a scarce-reserves framework. Without complicated administered rates, the New York Desk adjusted marginal reserve supply through daily Treasury trades or repos worth a few billion to tens of billions of dollars, guiding market borrowing rates close to target.
Postcrisis QE injected trillions in liquidity and greatly expanded reserves, moving the system irreversibly into an ample-reserves regime. Reserves ceased to be naturally scarce for most banks, and small open-market adjustments could no longer move prices effectively. Control shifted from funding quantities to administered rates supplied directly by the central bank.
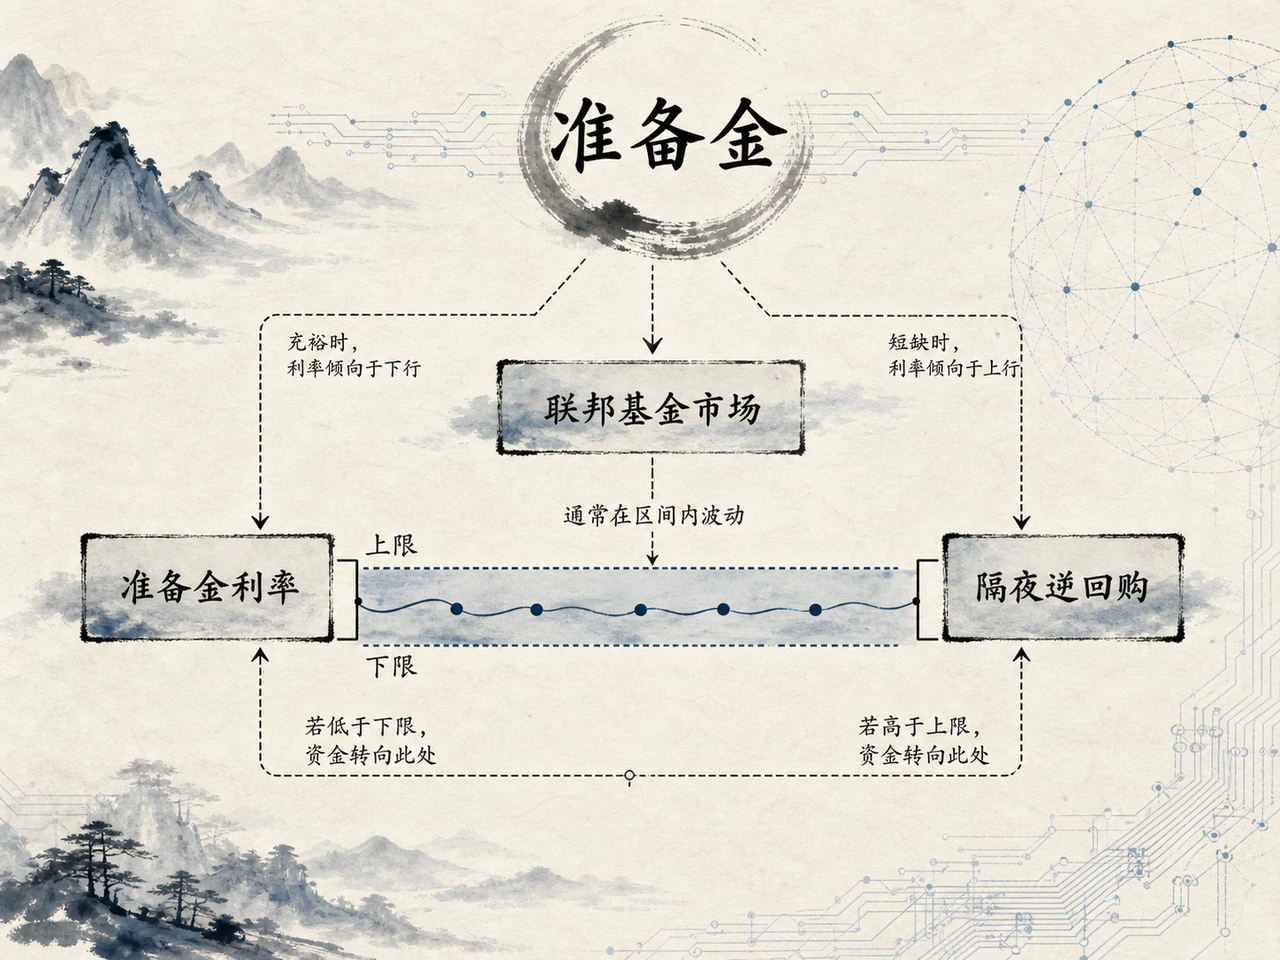
IORB and ON RRP: two administered rates underpin the rate corridor
Interest on reserve balances (IORB) is the main short-rate pillar under ample reserves, paid directly on eligible banks' central-bank reserves. Banks with Fed accounts can earn it risk-free, so a rational bank normally will not lend unsecured to peers at a substantially lower rate. It forms a theoretical lower bound for interbank lending.
Markets include more than banks. Some GSEs can hold Fed accounts but cannot earn IORB; money-market funds managing trillions and primary dealers cannot hold reserve accounts at all. Nonbanks with large overnight cash balances therefore lend at discounts, allowing actual rates below IORB and creating a structural gap in the floor.
The overnight reverse repo facility (ON RRP) addresses that gap, extending access to eligible large money-market funds, GSEs and major dealers. Against liquid Treasury collateral, the Fed borrows overnight cash from nonbanks at a fixed rate. Funds gain a safe direct Fed investment and will immediately shift cash there when private repo rates fall below the facility rate.
IORB and ON RRP create a flexible administered-rate defense, not a welded fixed rate. Counterparty credit, dealer balance-sheet costs such as supplementary leverage ratio (SLR) constraints, segmented liquidity and quarter- or year-end assessments create friction. Secured overnight markets, represented by SOFR, and unsecured EFFR retain changing spreads to the administered benchmarks. Successful implementation means short benchmarks remain consistently and smoothly anchored within the framework's intended range.
2. The Desk implements decisions; the balance sheet manages duration and liquidity
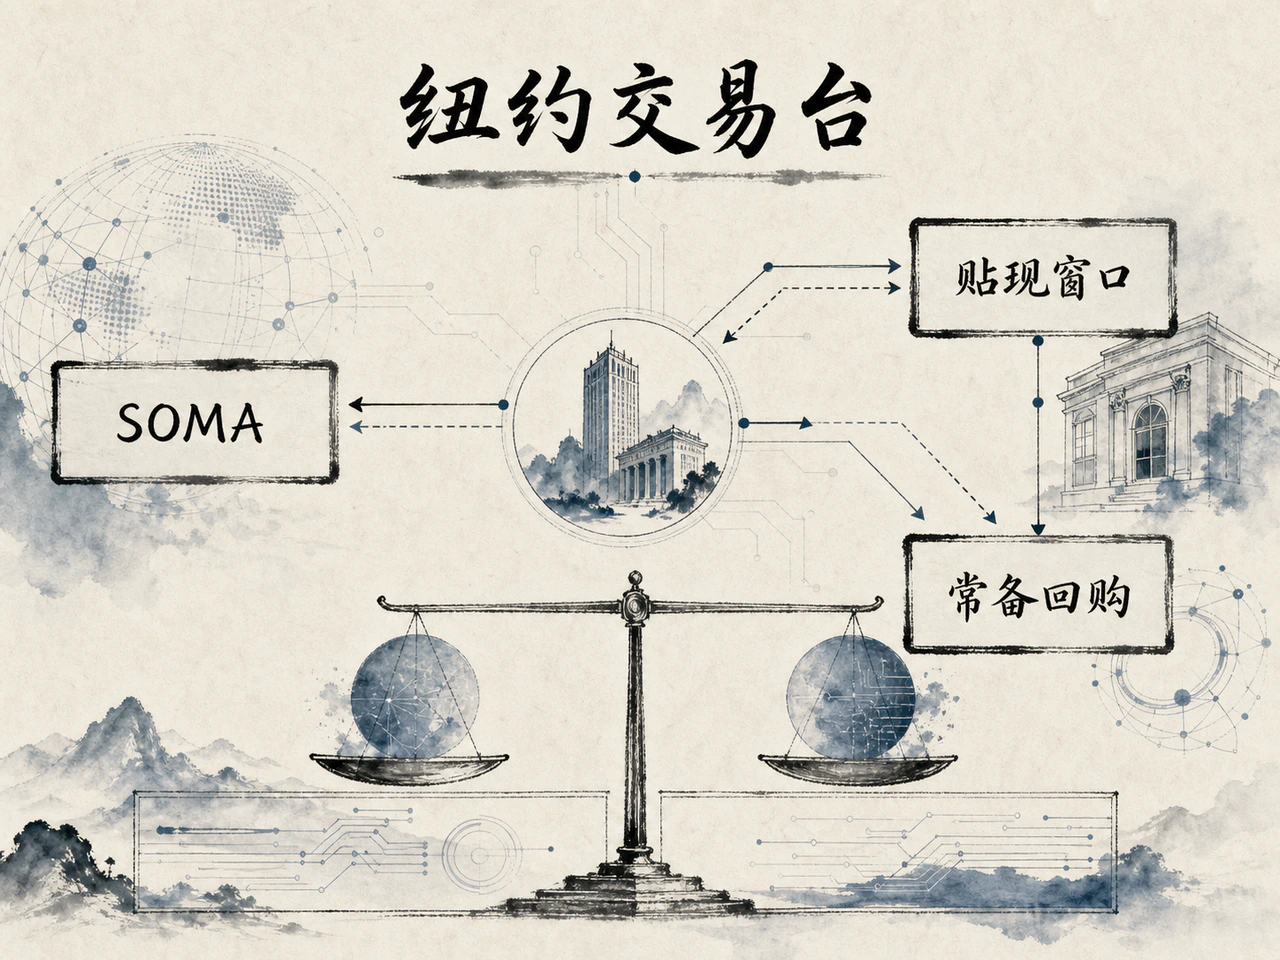
The Committee sets direction; New York converts instructions into market reality
If Washington's FOMC steers policy, the New York Fed's Open Market Trading Desk at 33 Liberty Street in Manhattan is its execution center, turning instructions into trades. Under domestic policy directives, it routinely buys and sells Treasuries and MBS and manages liquidity through a network of eligible major primary dealers.
Assets accumulated in open-market operations are held in the System Open Market Account (SOMA). This multitrillion-dollar portfolio legally belongs to the entire system, not a proprietary New York profit-and-arbitrage book. Its expansions and contractions reflect changing macro policy purposes.
Ordinary hikes and cuts mainly change overnight opportunity costs and the benchmark time value of funds. Balance-sheet tools, QE and QT, act directly on the stock and structure of system liquidity:
- Quantitative easing (QE): large secondary-market purchases of long Treasuries and MBS inject reserves and, crucially, absorb duration and convexity risk from private balance sheets. They compress long term premiums and economy-wide long financing costs, or supply liquidity as dealer of last resort when markets malfunction.
- Quantitative tightening (QT): caps on nonreinvestment let assets mature and be repaid by Treasury, or assets are actively sold. Securities shrink on the asset side and corresponding bank reserves are withdrawn and extinguished on the liability side.
Rate tools control short funding prices precisely; balance-sheet tools manage asset stocks and duration exposure. They can work together, but their different mechanisms and dimensions preclude a simple equation converting a given amount of runoff into an equivalent number of basis points of hikes.
Discount window and standing repo: different forms of liquidity need
Unexpected funding friction requires a carefully divided defense. The discount window and standing repo facility (SRF) are representative parts of the Fed's safety net:
The discount window dates to 1913 and provides standing collateralized emergency liquidity for eligible depositories. Against qualifying loans, bonds and other collateral, banks borrow at a preset discount rate. Use does not mean imminent failure; it often bridges temporary settlement lags or local deposit outflows. Its persistent difficulty is stigma: markets read use as financial distress, so banks may resist even near a funding break. The Fed has repeatedly required banks to prepledge collateral and conduct routine exercises to reduce that fear.
The SRF, by comparison, followed lessons from the September 2019 repo-rate spike. Transparent standardized open-market repos let primary dealers and eligible depositories exchange high-quality Treasuries and agency debt for overnight Fed liquidity. The purpose is a ceiling borrowing rate—a safety valve preventing uneven liquidity distribution from becoming localized shortages.
The discount window protects individual banks' ability to pay under extreme stress; standing repo smooths wholesale-market rate spikes and blockages. Counterparties, transaction instruments and institutional purposes differ distinctly.
3. Why cuts do not pull every long-term rate lower
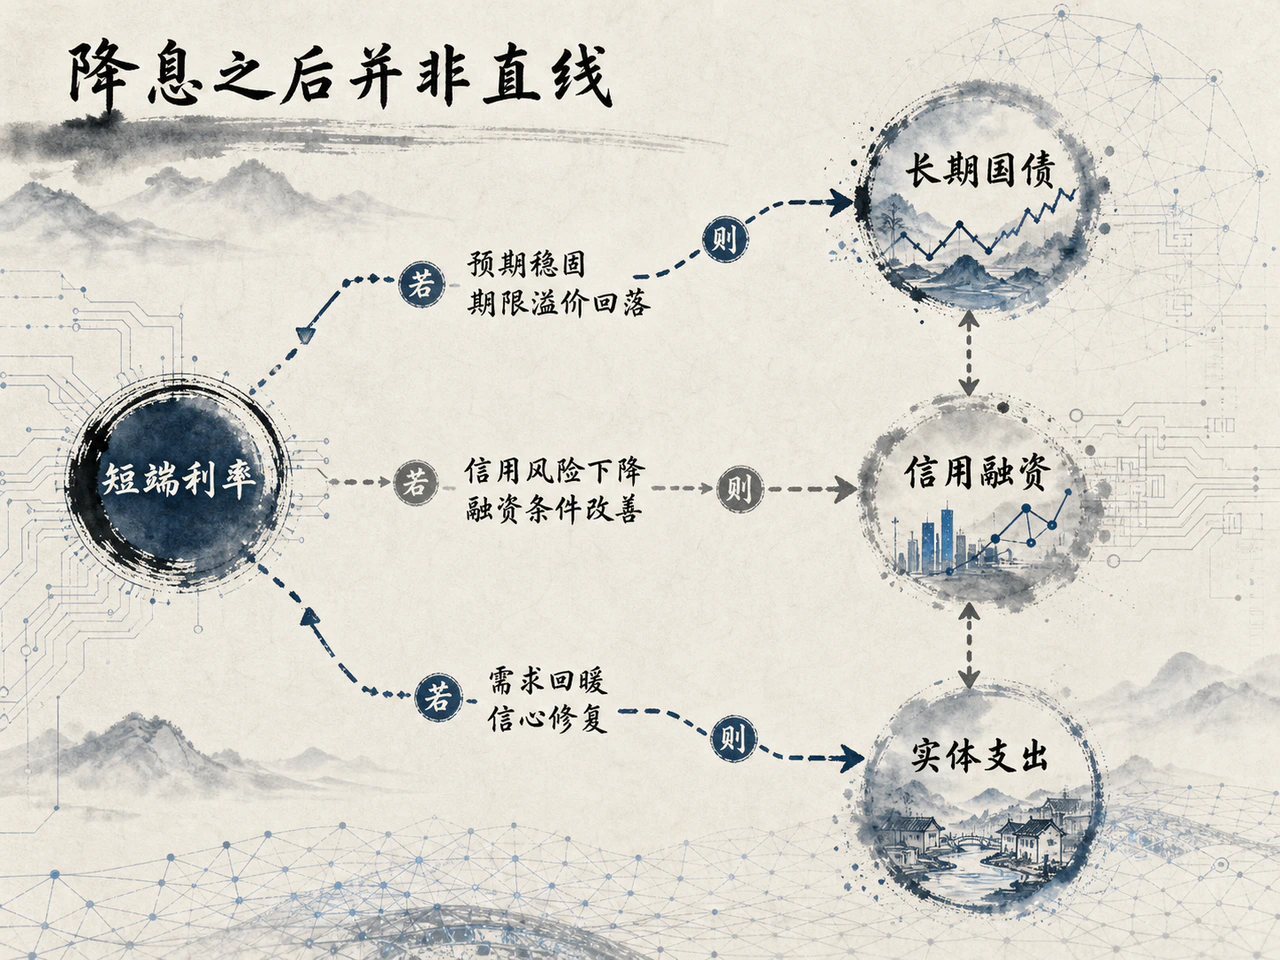
A whole spectrum of risk separates overnight rates from the 10-year yield
Once the Desk implements the policy rate, transmission leaves absolute central-bank control and enters a pricing world built by countless market participants. The intuition that cuts proportionally lower all borrowing costs is not how finance works.
The central 10-year Treasury benchmark can be roughly decomposed into average expected future short rates and a term premium. When the Fed cuts overnight rates, markets immediately reassess the macro meaning:
- If investors believe inflation is cooling faster and the cut is defensive easing as growth slows, expected future rate levels fall and long yields usually follow;
- If the cut signals premature accommodation or tolerance of inflation, or if demand remains strong, it may revive inflation concerns. Investors raise both long-run inflation compensation and the term premium for uncertainty, causing 10-year yields to rise rather than fall, repairing inversion or even producing bear steepening.
Long yields are also continually influenced by Treasury issuance, foreign reserve allocation, geopolitical safe-haven buying and high-frequency trading liquidity.
In corporate bonds, commercial-property loans and household mortgages, intermediary costs make the chain still more complex:
- Mortgage rates reflect not only the 10-year benchmark but agency-MBS spreads, prepayment-risk compensation and mortgage intermediaries' operating margins;
- Corporate costs depend on risk-free rates, default spreads, banks' deposit competition, capital requirements for risk-weighted assets (RWA) and internal risk appetite. If deteriorating conditions make banks tighten standards against bad loans, actual all-in business financing costs may rise despite a lower benchmark.
Printing money and draining liquidity: oversimplifying the balance sheet
Popular descriptions reduce expansion and contraction to opening a printing press or shutting a liquidity valve, then conclude prices must soar or liquidity vanish. This mechanical binary obscures the modern two-tier banking system.
When the Fed buys Treasuries under QE, payment is not physical cash in public pockets but newly recorded reserves. Reserves are banks' dedicated central-bank settlement assets and cannot directly buy real-economy goods or equities. Buying from nonbanks does create corresponding household or corporate bank deposits, but their conversion into investment, consumer credit and broader lending depends on borrowing appetite, expected real returns and bank capital. Without actual credit demand, excess reserves circulate among banks or short assets rather than spontaneously create excessive public purchasing power.
Similarly, QT reserve declines do not imply an equal evaporation of broad money M2. The liquidity-return process has several buffers:
- If drawdown is absorbed by ON RRP, money-market funds withdraw idle facility balances to buy newly issued, higher-yield Treasury bills, leaving bank reserves almost unscathed;
- Flows through Treasury's Fed cash account, the Treasury General Account (TGA), strongly offset reserves: taxes and issuance move reserves into TGA, while government spending returns liquidity to markets.
Assessing genuine shortages requires more than Fed total assets. Professionals watch overnight repo anomalies, sudden widening between nonbank funding spreads, and banks competing aggressively for wholesale money through high-rate certificates of deposit. These micro balance-sheet frictions determine whether transmission works smoothly.
Transmission is a conditional relay, not a certain switch. Washington sets the target, the Desk anchors short prices, traders and managers reprice the long risk-free curve and premiums, banks reassess capital and lending, and only then does policy slowly reach each mortgage and business expansion budget.
Congestion, delay or reversed risk appetite at any intermediary can greatly weaken or distort the initial intent. Announcing a rate decision merely pulls the trigger; how far it reaches and which financial or real sectors it affects remain determined by the network of intermediaries and market interactions.