The US government collects more than $5 trillion annually yet still faces a fiscal gap approaching $2 trillion. Debt interest is growing faster than revenue, consuming room for deficit reduction.
According to news alerts from the September 15 House hearing, Treasury Secretary Bessent said keeping the federal deficit within 3% of GDP would help repay debt and was crucial to stabilizing the Treasury yield curve.
A 3% deficit can help debt grow more slowly than the economy, gradually reducing the servicing burden. But while spending exceeds revenue, borrowing generally must continue. Whether 3% stabilizes debt depends on growth; achieving it depends on revenue increases and spending restraint approaching $1 trillion annually.
The US can still repair its finances, but revenue growth and spending discipline must reach the budget. Sustained Treasury yield declines depend both on delivering deficit promises and on reform's effects on growth and inflation.
I. Interest consumes revenue gains; deficit reduction faces a near-trillion-dollar gap
Pandemic emergency spending has ended, but US finances have not returned to their pre-pandemic position.
OMB historical data published through FRED show fiscal 2019 revenue around $3.46 trillion and spending $4.45 trillion, already leaving a nearly $1 trillion deficit. Emergency spending surged in 2020–2021, producing deficits above $2.7 trillion in both years. Withdrawal of relief narrowed the gap temporarily without restoring balance; since 2023 it has settled around $1.7 trillion–$1.8 trillion.
| Federal fiscal year | Revenue | Spending | Deficit | Net interest |
|---|---|---|---|---|
| 2019 | 3.46 | 4.45 | 0.98 | 0.38 |
| 2020 | 3.42 | 6.52 | 3.10 | 0.35 |
| 2022 | 4.90 | 6.27 | 1.37 | 0.48 |
| 2024 | 4.92 | 6.74 | 1.82 | 0.88 |
| 2025 | 5.24 | 7.01 | 1.77 | 0.97 |
All table amounts are US$ trillions, using historical data updated April 2026.
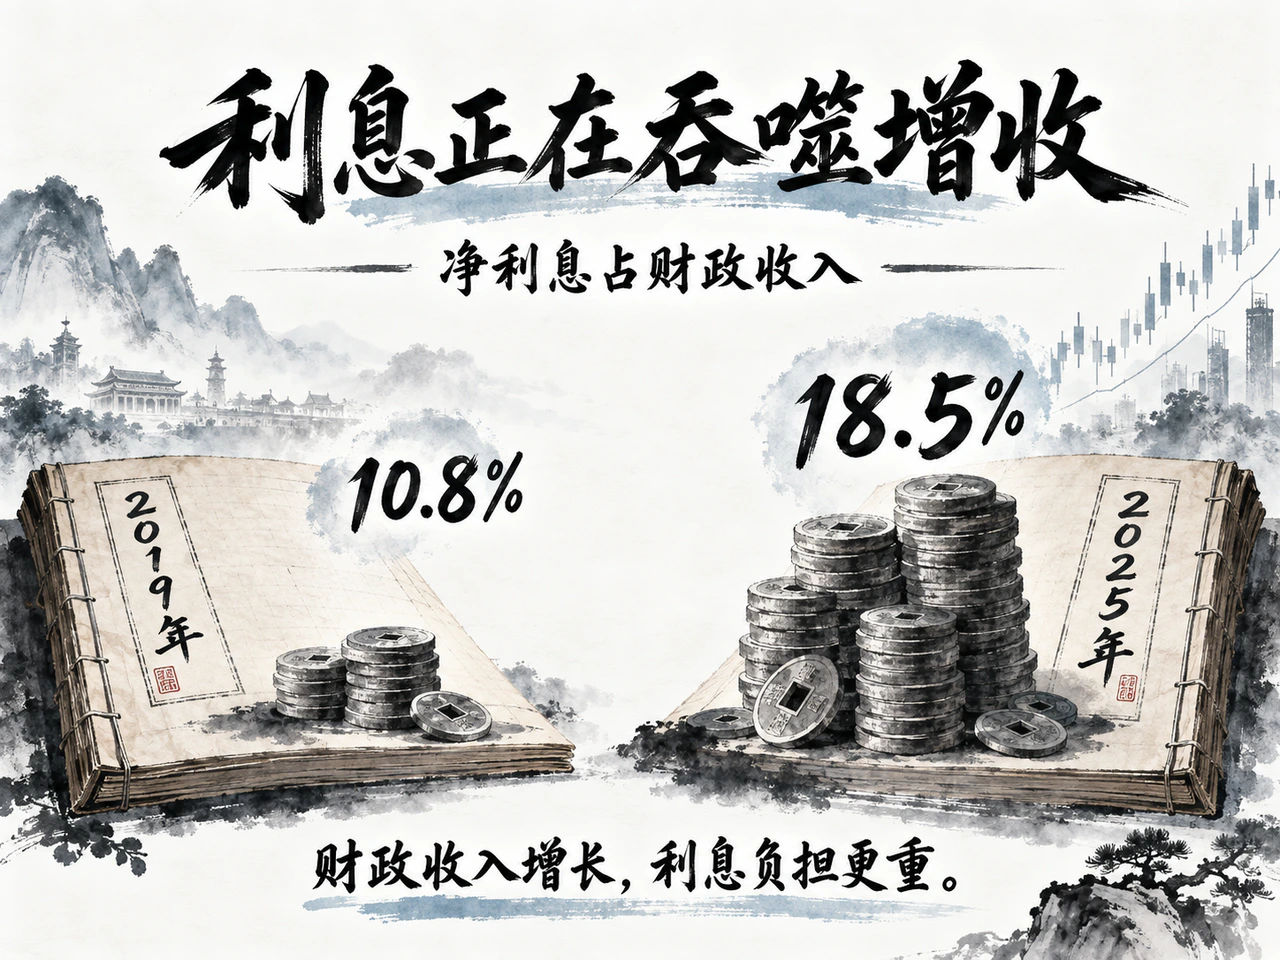
From 2019 to 2025, revenue rose approximately 51% and spending 58%. Net interest changed more dramatically: up around 159% in six years, increasing from 10.8% to 18.5% of revenue. About $18.5 of every $100 collected now goes to net interest.
The annual deficit expanded approximately $791.1 billion over that period: about $594.9 billion from higher net interest and $196.2 billion from the wider noninterest gap. Both rates and debt size raise interest; debt costs are an unavoidable obstacle to budget repair.
The contrast is 2020: borrowing surged but net interest fell, as low rates temporarily obscured the cost of debt expansion. Since then, low-coupon debt has matured and higher funding costs have entered budgets. Today's bill reflects years of debt accumulation and repricing together.
At fiscal 2025 year-end, gross federal debt was about $37.4 trillion, partly held by government accounts such as Social Security. CBO recorded publicly held debt near $30.2 trillion, or 99.4% of GDP, including Fed-held Treasuries and more directly reflecting funds raised from markets. Recent media figures above $40 trillion use later-dated gross debt and differ in scope.
Revenue kept growing in 2026, but some apparently favorable budget changes reflect payment timing.
Treasury data compiled by the Joint Economic Committee show the first 11 fiscal months through August with about $4.845 trillion revenue, $6.811 trillion spending and a $1.966 trillion deficit. Revenue grew 3.29%, faster than spending's 2.20%, modestly narrowing the unadjusted deficit. CBO's earlier preliminary monthly estimate, however, put the timing-adjusted deficit approximately $82 billion wider. Better monthly or cumulative cash flows alone do not establish structural deficit reduction.
Tax categories diverged. CBO estimated first-11-month individual income and payroll taxes up $239 billion, but corporate income taxes down $96 billion, approximately 25%. Jobs and wages support receipts, while the 2025 tax law's expanded investment deductions bring tax benefits forward ahead of growth gains. Investment may raise future capacity, but current revenue falls first.
Tariffs have not provided stable incremental revenue sufficient to reverse the budget. Net customs receipts over 11 months were about $167 billion, broadly unchanged year on year as refunds offset collections. On August 20 CBO projected fiscal 2026 net customs revenue roughly $250 billion below its February baseline; policies implemented through July 31 would add approximately $900 billion to cumulative 2027–2036 deficits, including extra interest.
Benefits, interest and defense continue growing. Adjusting for payment timing, CBO estimated first-11-month Social Security, Medicare and Medicaid spending up a combined $198 billion, net interest up $111 billion, and Defense Department military spending up approximately $41 billion. Some education-spending reductions include student-loan cost reestimates, which cannot readily recur as annual savings.
Tax preferences, tariff refunds and growing benefits and interest substantially absorbed deficit relief from wage-related receipts. In August, CBO raised its full-year 2026 deficit estimate from February's approximately $1.9 trillion to $2.1 trillion, mainly because revenue disappointed.
Persistent gaps explain Bessent's emphasis on 3%. Stability depends on new borrowing relative to growth. With prior-year debt at 100% of GDP and nominal GDP growing 4%, a total deficit around 3.85% of current GDP stabilizes the ratio; 3% gradually lowers it. At only 2% nominal growth, stabilization permits a deficit around 1.96%, making 3% too high.
**A 3% deficit is neither a growth-independent safety threshold nor the point where debt principal starts declining in net terms.** Its value is reducing new borrowing so the economy can outgrow debt.
Achieving the target requires improving the primary balance, excluding net interest. CBO's February estimate put 2026 interest at around 3.3% of GDP. With that burden, a 3% total deficit requires a small noninterest surplus. If interest reaches 4.6% of GDP in 2036, the same total target requires a primary surplus near 1.6%. More interest leaves less room for other spending.
At CBO's projected 2028 nominal GDP of approximately $34.67 trillion, 3% means about $1.04 trillion deficit. Relative to the timing-adjusted baseline, improvement of about $916 billion is needed; using unadjusted annual figures, the gap is approximately $1.04 trillion. Both imply nearly $1 trillion annually, roughly the scale of an entire year's nondefense discretionary spending then.
These gaps use CBO's February medium-term baseline, excluding later tariff and rate changes and possible reform-induced growth and interest savings. Even so, they far exceed what cuts to a few administrative departments can solve.
The US substantially repaired its budget in the 1990s. Between 1993 and 2000, revenue rose from approximately $1.15 trillion to $2.03 trillion, about 75%, while spending grew only 27%. A $255.1 billion deficit became a $236.2 billion surplus.
That history combined tax increases, spending restraint, strong growth and buoyant asset markets. The 1990 budget reform introduced spending caps and PAYGO, requiring offsets for new tax cuts or mandatory spending; 1993 revenue measures further narrowed the gap. Revenue had to catch spending by enough to turn deficit into surplus.
Today aging-related spending, debt and interest are heavier, while defense faces expansion demands. Repeating 1990s progress still requires revenue, discipline and growth together, but adjustment room is narrower.
II. Budget reform determines long-bond potential; buybacks cannot replace deficit reduction
Deficit reduction is most vulnerable when savings accompany even larger spending and tax-cut promises. The budget must show actual net improvement.
CBO estimated in February that even including growth feedback, the 2025 reconciliation law would add around $4.7 trillion to 2026–2035 cumulative deficits, including interest. Extra revenue from stronger growth still would not cover its fiscal cost.
The 2027 presidential budget also shows trade-offs. CBO's June assessment put ten-year mandatory spending up $351 billion, defense discretionary spending up $2.4 trillion and nondefense discretionary spending down $2.6 trillion. These rounded figures show cuts almost offset by other increases. With no revenue proposals or full deficit/debt projections, the request is closer to reprioritizing spending and does not yet explain the 3% target.
Revenue could rise through a broader tax base. Restricting inefficient deductions, narrowing exemptions and better administration can help. CBO estimated 2026 tax preferences around $2.6 trillion, but this is no immediately collectable pool: provisions interact, repeal changes behavior and affects health insurance, retirement saving and investment, requiring individual assessment.
Tariffs raise revenue from a narrower, unstable base. Higher rates change imports; exemptions, negotiations and courts affect collections. Higher import costs may also raise inflation and borrowing costs. Budgets cannot simultaneously assume large import substitution and an unchanged long-run import tax base.
Spending reform cannot indefinitely exclude major items. Mandatory spending, net interest and defense discretionary spending were roughly 86% of 2025 outlays. Excluding them leaves too little budget to fill persistent gaps. Social Security changes can address the payroll tax base, benefit structure and phased parameters; health programs need better payment incentives and lower inefficiency. Each entails explicit distributional choices.
The 2026 trustees report projects Old-Age and Survivors Insurance reserves exhausted in Q4 2032, after which continuing income covers about 78% of scheduled benefits. Revenue does not disappear; the financing-benefit gap needs resolution. Earlier gradual reform offers more chance of avoiding abrupt adjustment at exhaustion.
Growth eases tensions gradually. CBO projects average annual real GDP growth around 1.8% in 2027–2036. Raising it persistently to 3%, all else equal, leaves real output about 3.6% above baseline after three years and 12.4% after ten. Even proportional revenue growth adds only a little over $200 billion to an approximately $6 trillion revenue base after three years, far short of nearly $1 trillion in annual adjustment.
Productivity, participation and effective investment enlarge future tax bases; better returns may also raise real rates. Faster growth need not mean cheaper financing. Budgets should first rest on executable revenue and saving measures, with upside growth accelerating deficit reduction.
Expanded Treasury buybacks are easier to implement rapidly than fiscal reform, but mainly address market liquidity.
On August 19, Treasury announced raising some long-bond liquidity-support buyback caps from $2 billion per operation to at least $4 billion. The September 9 schedule set a $6 billion cap for the September 10 operation in 10–20-year maturities. Buybacks improve illiquid off-the-run bonds and dealer inventory pressure, but caps are not actual traded amounts.
If new borrowing funds buybacks, the government merely alters liability structure. Replacing long bonds with bills can reduce market duration risk while increasing exposure to future short rates and rollover funding.
Buying old debt at discounts likewise does not create equivalent fiscal profits. Discounts usually reflect coupons below current rates; funding purchases of low-coupon bonds with costlier new debt requires comparing future cash flows, not just canceled face value. Debt management can improve financing conditions; fiscal repair still requires net changes in revenue and spending.
Assessing sustained yield effects requires understanding long-rate drivers.
Long rates broadly contain the expected average of future short rates and a term premium for bearing long-term risks. A more credible fiscal path and lower future net funding needs help reduce risk compensation. If deficit reduction also eases demand and inflation, expected policy rates may fall.
Daily Treasuries reflect many drivers. On September 14, Treasury's daily 2-year, 10-year and 30-year yields were 4.65%, 4.97% and 5.34%. Compared with September 8, they rose 26, 17 and 9 basis points on the same basis, narrowing 2s10s from 41 to 32. Larger short/intermediate rises show the selloff cannot all be attributed to long-term fiscal risks.
Inflation still shapes pricing. August CPI rose 0.4% month on month and 3.4% year on year. Gasoline's 3.9% monthly rise contributed over one-third of headline gains; core CPI rose 2.4% annually. Energy and broader prices differ, and the Fed's responsibilities extend far beyond government financing costs.
The September 14 10-year real Treasury yield was 2.60%, showing real financing costs also support high nominal rates. Subtracting nominal and real par yields gives approximately 2.37 percentage points, only a rough inflation-compensation measure rather than pure expected inflation.
Simplified scenarios illustrate fiscal repair's medium-term value. Starting from publicly held debt at 100.6% of GDP at end-2026, assume constant total deficits and nominal growth for ten years, ignoring other financing adjustments:
| Annual total deficit/GDP | Nominal GDP growth | Debt/GDP after ten years |
|---|---|---|
| 6% | 4% | 118.6% |
| 3% | 4% | 93.3% |
| 6% | 5% | 110.4% |
| 7% | 3% | 136.4% |
These compare fiscal-growth combinations, not forecasts. Immediate achievement of 3% is only an assumption; multiyear implementation adds transition debt and raises the final ratio. Even with a 3% deficit and 4% nominal growth, nominal debt rises about 37% over ten years while its relative economic burden falls.
Fiscal improvements can substantially affect rates but should not be mapped mechanically. Historical Fed research estimates around 15–25 basis points of long-rate change per 1-percentage-point deficit change. A sustained 3-point improvement could correspond to several tens of basis points as an order of magnitude, but sample, horizon, growth and prior pricing differences prevent treating this as today's 10-year yield target.
Lower costs help budgets in turn. CBO's April sensitivity analysis estimated that rates persistently 0.1 percentage points above baseline across maturities add about $379 billion to cumulative 2027–2036 deficits. Lower rates likewise reduce burdens, but savings emerge gradually as old debt matures and refinances, not immediately across all debt.
Over the next 6–12 months, the strongest repair evidence will be congressional budget proposals with concrete provisions and credible scoring, plus sustained narrowing of primary deficits after special factors. Buyback size, monthly cash flows and auction schedules affect trading but cannot independently change the medium-term fiscal assessment.
In 2027–2030, credible revenue/spending reform with stable growth could lower 10–30-year risk compensation. If fiscal contraction materially weakens growth, short/intermediate yields may fall more; a steeper curve need not imply weaker fiscal credibility. Recession-driven yield declines reduce taxes and raise unemployment benefits and similar spending, potentially worsening balances.
Postwar history shows forced rate suppression has costs. The Fed fixed bill yields at 0.375% and maintained an implicit long-Treasury ceiling around 2.5% until the 1951 Treasury-Fed Accord ended the arrangement. Cheap government financing constrains anti-inflation policy; weakened monetary credibility today could raise long-run risk compensation.
**Whether Bessent's 3% target stabilizes Treasuries ultimately depends on bringing noninterest balances gradually near balance and easing debt burdens through productivity and stable inflation.** Fiscal repair reliably supports lower Treasury yields only when budget changes convince investors that future borrowing will persistently decline.


