Only three weeks remain until the November 3 US midterm elections. Silver Bulletin's latest polling averages give Democrats an 8.8-percentage-point lead on the generic congressional ballot, while its presidential net-approval measure shows the share opposing Trump exceeding support by 22.4 points. With an extremely narrow seat advantage, Republicans face a serious challenge in the House. If pivotal districts flip and the House changes hands, the Trump administration will lose a dependable congressional route for additional tax cuts and spending over the next two years.
That does not mean fiscal policy would reverse quickly. The 2025 tax-and-spending law, P.L. 119-21, made several earlier core tax cuts permanent, establishing the medium- to long-term deficit baseline. A reshaped Congress directly determines the feasibility of new policies, but would struggle to reverse the established deficit trajectory in the short term.
By the early hours of October 13 Beijing time, a Republican loss of the House had become the baseline forecast, with a risk of losing the Senate as well. Control of the chambers creates distinct institutional constraints on budget approval and confirmation of appointments. Financial markets need to distinguish the effects of incremental fiscal policy, growth and inflation expectations, and risk premiums arising from cross-party bargaining.
1. Election Scenarios: Democrats Have More Than a 75% House Chance; Senate Control Depends on Key Battlegrounds
The midterms elect the entire House and part of the Senate, not the president. Trump is not on the ballot. The governing setback markets are considering mainly means Republicans losing control of at least one chamber. The new Congress takes office on January 3, 2027; after November's vote, the incumbent Congress will still control the year-end 2026 lame-duck session.
The House currently has 218 Republicans, 214 Democrats, one independent and two vacancies. All 435 seats are up for election, and a majority of 218 confers control. The 8.8-point Democratic lead in Silver Bulletin's October 12 generic-ballot average is filtering through individual districts into seat contests.
Leading forecasting models are closely aligned on House control:
| Forecaster and public update | Probability Democrats Retake the House | Model Characteristics and Main Projection |
|---|---|---|
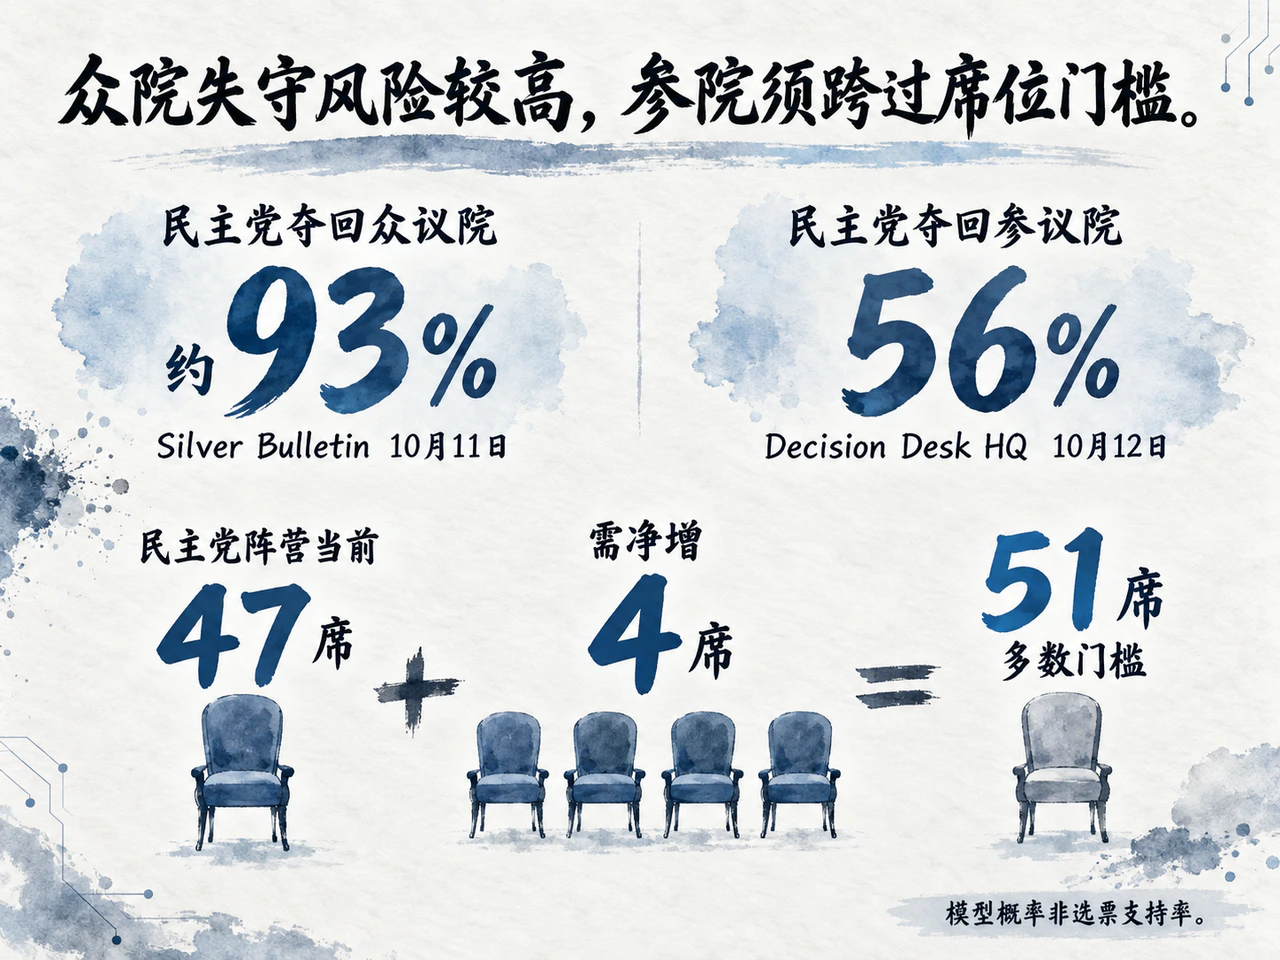
| Silver Bulletin (October 11) | Approximately 93% | FLIPR Deluxe model combines district polling, economic fundamentals and expert ratings |
| Decision Desk HQ (October 12) | More than 75% | Simulations put Democrats' average House seat count at approximately 235 |
Although models handle district fundamentals, turnout and historical polling errors differently, all view a Democratic House takeover as highly likely. Cook Political Report estimates that this redistricting round gave Republicans a net cushion of roughly four seats, but that cannot fully offset the national polling headwind. The Republican path to retaining the House has become very narrow.
The Senate remains more uncertain. Republicans currently hold 53 seats; Democrats hold 45, plus two independents caucusing with them, giving the Democratic caucus 47. Democrats must gain a net four seats to reach the 51-seat majority threshold. In a 50:50 tie, the Republican vice president retains the deciding vote. Decision Desk HQ's October 12 figures put Democrats' Senate takeover probability at 56%. Contests in Maine, North Carolina, Alaska, Ohio, Iowa and Texas will determine the balance. Losing both chambers is now a material scenario markets must consider.
2. Policy Divergence and Asset Transmission: Existing Deficits Persist; Limits on New Stimulus Could Favor Treasuries
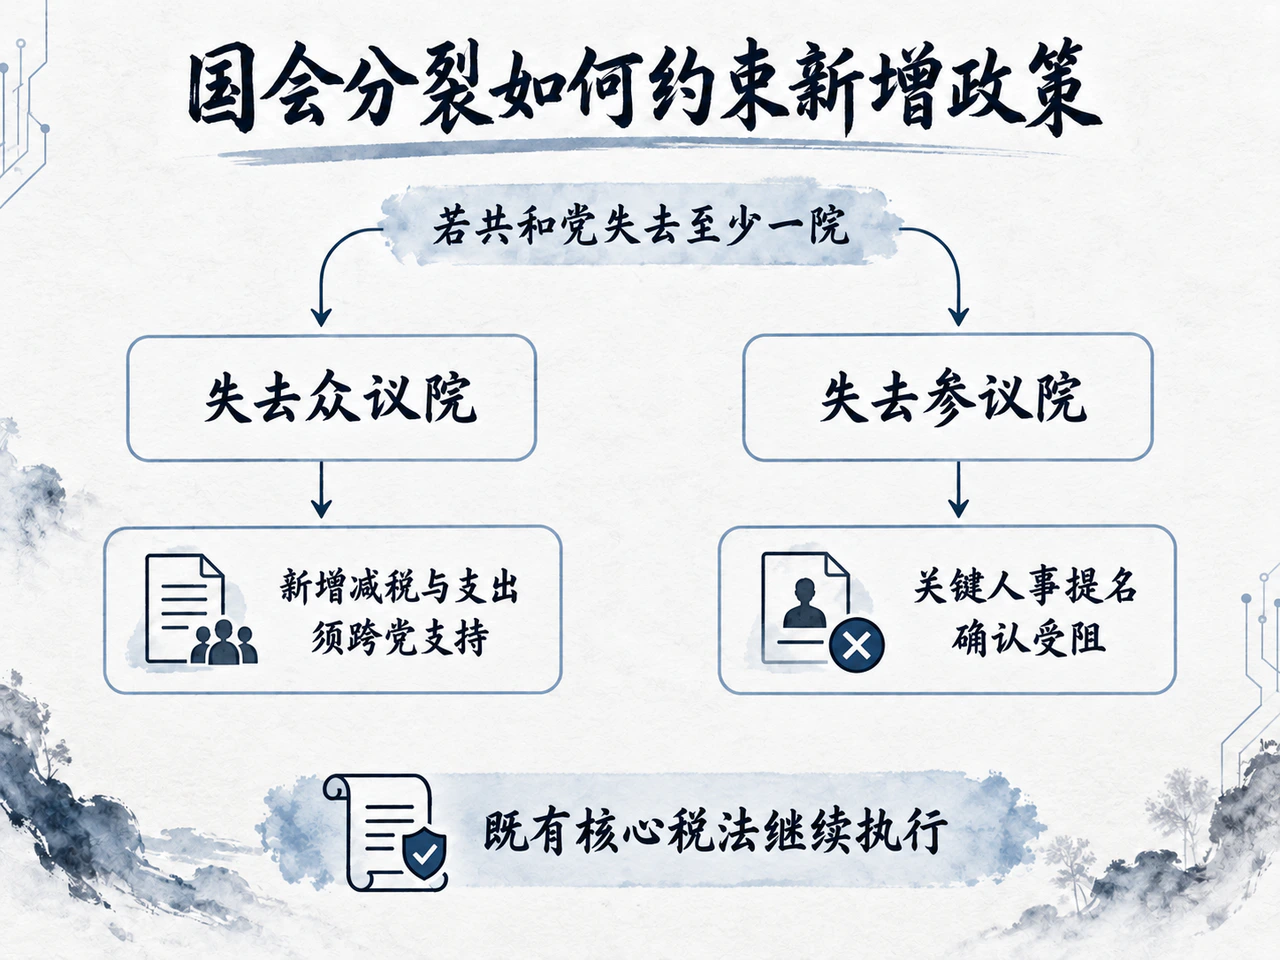
Divided congressional control directly determines the dimensions of policy constraint:
| Election Outcome | Main Changes to Fiscal Legislation | Main Changes to Financial Policy and Appointments |
|---|---|---|
| Lose the House only | New tax cuts and changes to benefits and spending require cross-party support; annual appropriations negotiations become harder | Senate confirmations remain accessible; executive and existing regulatory powers face no direct impact |
| Lose the Senate only | Single-party budget legislation is also obstructed | Democrats can block or delay key regulatory nominations, making it harder to assemble the administration |
| Lose both chambers | Single-party fiscal legislation ends completely; congressional budget scrutiny and investigations of the administration intensify | Both legislation and confirmations face constraints, while existing law and presidential executive orders remain effective |
Fiscal policy: existing tax law provides strong continuity, while routes to additional expansion risk being blocked.
The 2025 tax-and-spending law, P.L. 119-21, made permanent core provisions of the 2017 tax cuts, including individual income-tax rates. Winning one or both chambers would not automatically end them. Repealing existing law requires passage in both chambers and the president's signature, or two-thirds majorities in each chamber to override a veto. The current tax baseline is institutionally highly durable during Trump's term.
The route to new policy is what would be blocked. Reconciliation, previously used by Republicans to bypass the Senate's 60-vote threshold, requires both chambers to pass the same budget resolution containing reconciliation instructions. Losing the House would eliminate the Republicans' ability to use reconciliation unilaterally for tax cuts or spending restructuring.
Several expiring or new initiatives would consequently face reassessment. The 2025 law's income-tax deductions for tips and qualified overtime apply only in tax years 2025–2028, requiring new legislation for an extension. Trump's September 9 promise of a $5,000 dividend to every adult American citizen, reiterated by the White House on September 10, would be almost impossible to enact through one party alone without firm control of both chambers.
A divided Congress reduces the feasibility of further single-party stimulus, but does not imply a substantial deficit contraction. CBO's conventional estimate of the 2025 tax law shows an approximately $3.4 trillion cumulative increase in deficits over 2025–2034 relative to the January 2025 baseline, excluding macroeconomic feedback and additional interest. Preliminary figures in CBO's October 8 monthly report put the fiscal 2026 federal deficit near $2.0 trillion. Social Security, Medicare and unavoidable debt-interest outlays are driven by existing statutory spending.
History also shows that divided government need not bring austerity. In 2019, Trump and the Democratic-controlled House reached a bipartisan budget agreement that raised combined defense and nondefense spending caps for fiscal 2020 and 2021 by $322 billion and suspended the debt ceiling. The 2025 legislation also raised the ceiling by $5 trillion, so the midterm result itself would not immediately trigger a new debt-limit crisis. Fed research nevertheless found that the 2011 and 2013 debt-limit confrontations added event premiums of roughly four to eight basis points to Treasury yields. Friction in subsequent debt-limit negotiations could still raise financing costs in parts of the market.
Monetary policy, regulation and trade: executive authority continues, while appointments face bargaining.
Monetary-policy independence already has an institutional anchor in leadership appointments. Kevin Warsh became Federal Reserve Board chair on May 22, 2026, for a term through May 2030, following Senate confirmation in May. The midterms affect only confirmation of possible future Board vacancies and cannot reset existing Fed leadership. Congress's substantive monetary-policy impact mainly operates indirectly through the effects of reduced incremental fiscal support on demand, employment and inflation.
Financial and digital asset regulation separates implementation under existing law from new legislation. The GENIUS stablecoin law passed in 2025 is already enacted, allowing agencies' rulemaking to proceed through established procedures. The CLARITY digital asset market structure bill, focused on trading architecture, failed a Senate procedural vote on September 15; a new Congress will reshape its legislative bargaining boundaries. A Republican Senate loss would also directly increase resistance to confirming senior financial regulators.
Tariff policy retains considerable executive discretion. Although the Supreme Court rejected presidential tariff authority under the International Emergency Economic Powers Act (IEEPA) on February 20, 2026, an October Congressional Research Service review shows the administration still making extensive use of statutory powers including Section 232 of the Trade Expansion Act and Section 301 of the Trade Act. Democratic congressional control could intensify hearings and oversight, but changes to those authorizing laws would still face a presidential veto. Tariff barriers would not quickly recede simply because Congress changes hands.
Transmission to asset prices:
- Treasuries: Compared with additional deficits under a Republican sweep, a divided Congress blocks incremental stimulus legislation, easing expectations of future Treasury supply expansion and structurally supporting bond prices. Yet the roughly $2 trillion fiscal 2026 deficit shows that financing needs remain large. Combined with possible liquidity friction from debt-limit bargaining, this may limit the decline in the term premium and leave less room for long yields to fall than short yields.
- The dollar: If constraints on new fiscal stimulus coincide with softer growth momentum and stronger rate-cut expectations, the dollar's interest-rate advantage would weaken. But divergent growth outside the US, together with safe-haven demand from global trade friction generated by executive tariff tools, makes wide fluctuations more likely than a one-way dollar decline.
- Equities: Disappointment over further corporate tax cuts and broad deregulation, together with cooling momentum's effect on earnings expectations, creates a headwind for risk assets. Lower risk-free rates provide some valuation support through discount rates, but policy uncertainty raises the equity risk premium. Valuation sensitivity in heavily regulated sectors such as finance and digital assets will depend more on detailed executive rules and the costs of bipartisan friction.
Trump's central midterm risk is losing the initiative to legislate through his own party alone. If Republicans lose at least one chamber, policy over the next two years will shift toward cross-party deals and contests over executive power. Single-party incremental fiscal expansion will be constrained, while the established trillion-dollar deficit baseline continues to dominate the macroeconomic environment.
(This article is macroeconomic policy and market research and does not constitute investment advice.)


