By the morning of October 22, Beijing time, U.S. payment-stablecoin regulation had entered the implementation phase. On October 21, the Office of the Comptroller of the Currency (OCC) announced its final rules implementing the GENIUS Act, specifying an effective date of January 18, 2027. With requirements for stablecoin issuance, reserve management, redemption, custody and capital finalized, institutional competition was shifting toward preparing license applications, investing in compliance and expanding specific payment businesses.
Formal applications await approval of forms; eligible existing firms may receive a 12-month transition

The rules apply to payment-stablecoin issuers, foreign issuers and related custody activities under OCC jurisdiction, covering reserve assets, redemption mechanisms, risk management, audit reporting, capital adequacy and operational safeguards. Bank subsidiaries, nonbank issuers seeking federal qualification and state-level issuers legally brought within OCC oversight must all prepare for compliance through their applicable routes. Related rules on anti-money laundering, the Bank Secrecy Act and sanctions compliance will be developed separately by the OCC in coordination with the U.S. Treasury.
As for the timing of admission, publication of the final rules did not immediately open the formal application channel. Under guidance released concurrently by the OCC, the information-collection arrangements for the relevant application forms must receive Office of Management and Budget (OMB) approval before the OCC begins accepting applications and exemption requests. The start date will be announced separately.
Transition arrangements directly affect continuity of existing businesses. When the rules take effect on January 18, 2027, eligible applicants that have submitted a substantially complete application still under review may receive an OCC exemption of up to 12 months within statutory limits. The OCC generally expects to support applications by qualifying existing issuers for temporary relief from the prior-approval requirement, reducing the disruption from the approval process. Exemptions from other regulatory requirements still require specific justification, while new entrants should in principle obtain approval before starting business. Existing firms therefore need to document their reserve allocation, redemption arrangements, management team, capital and liquidity, and third-party service agreements during the application window, securing a substantially complete determination and transitional relief to reduce uncertainty around the business transition.
Existing reward programs receive no presumption of compliance; regular reporting is planned for next year's first quarter
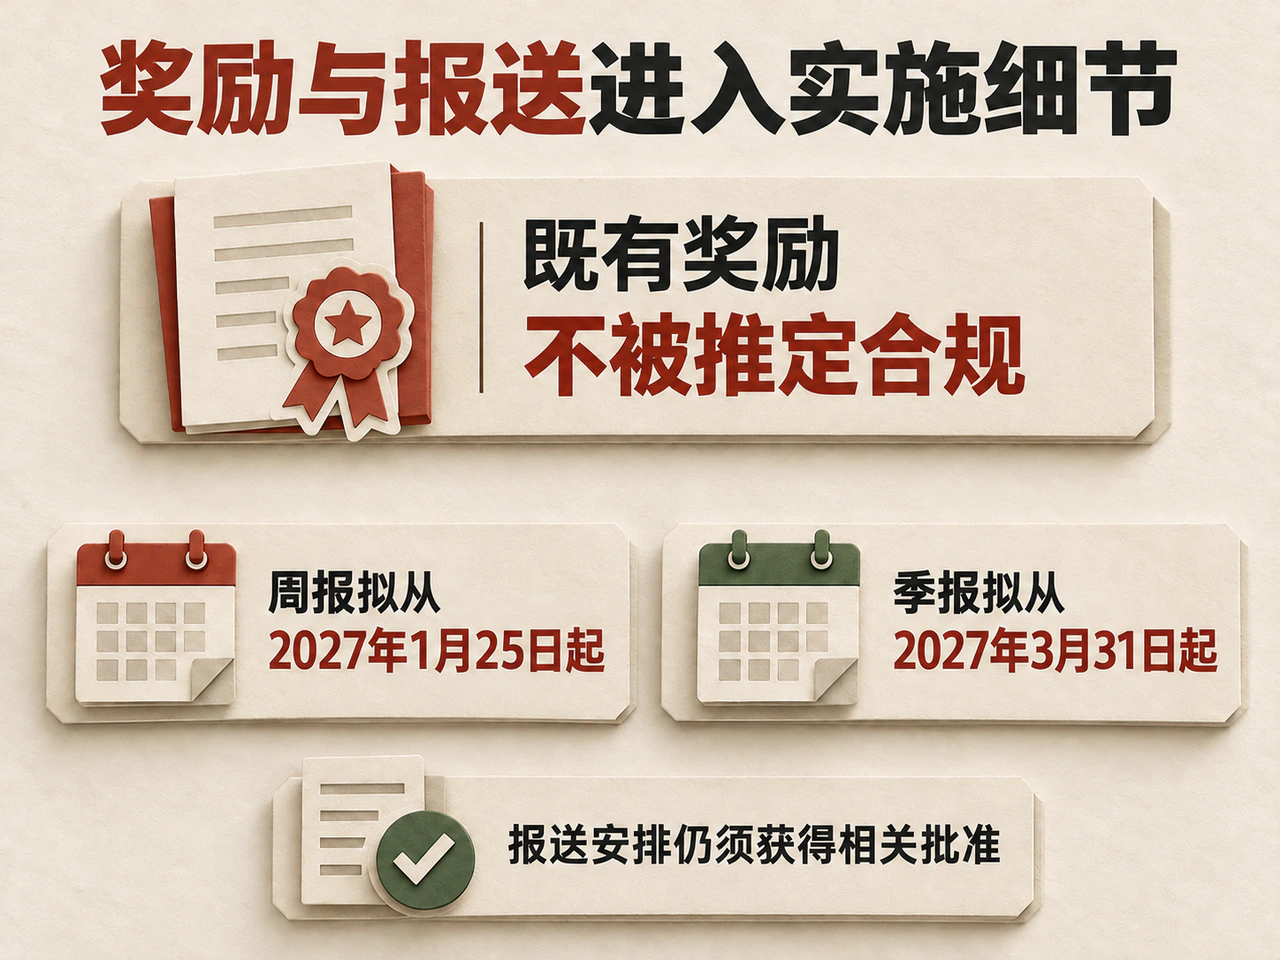
Stablecoin reward programs remain a point where regulatory scrutiny meets business models. According to CoinDesk's coverage of the final rules, the OCC will apply the Act's restrictions on yield payments according to the specific business arrangement. Existing reward programs will not be presumed compliant simply because they predate the Act, and regulators have not attempted to cover every situation through a simple set of examples.
The underlying funding arrangements between issuers and trading platforms therefore become central to compliance determinations. Who pays the rewards, which user behavior they reward and their commercial purpose will all affect regulatory treatment. Platforms relying on rewards to encourage users to hold coins will face tighter compliance constraints on product design and partnership agreements. Corporate settlement services, meanwhile, must demonstrate actual improvements in payment efficiency, access to funds and usage costs.
Standard Chartered's October 21 article on institutional stablecoins likewise proposed layered risk controls based on business use. Bank representatives said cross-border corporate payments, treasury transfers and trading or investment activities should have controls tailored to their respective customers, counterparties and fund flows, with issuer, reserve, redemption, wallet-custody and network risks assessed together. Commercial payments between known businesses with identified counterparties require markedly different monitoring from funds moving frequently through exchanges, personal wallets and cross-chain routes.
This segmentation by business use will also connect with ongoing regulatory reporting. On October 21, the OCC published revised weekly and quarterly reporting forms and continued to seek comments. Subject to the necessary approvals, the two types of reports are intended to apply from reporting dates of January 25 and March 31, 2027, respectively, bringing issuers' reserve management, financial condition and operational capacity into a regular reporting framework.
As U.S. stablecoin regulation moves from legislation to implementation, institutional competitive advantages will increasingly lie in verifiable reserve and redemption mechanisms, sustained risk-control capabilities and reliable delivery of payment services. The market's next priorities are when formal applications will open, how existing businesses will complete the transition, and whether corporate payment use cases can generate sustainable commercial demand.
Click Read Original for full details.


